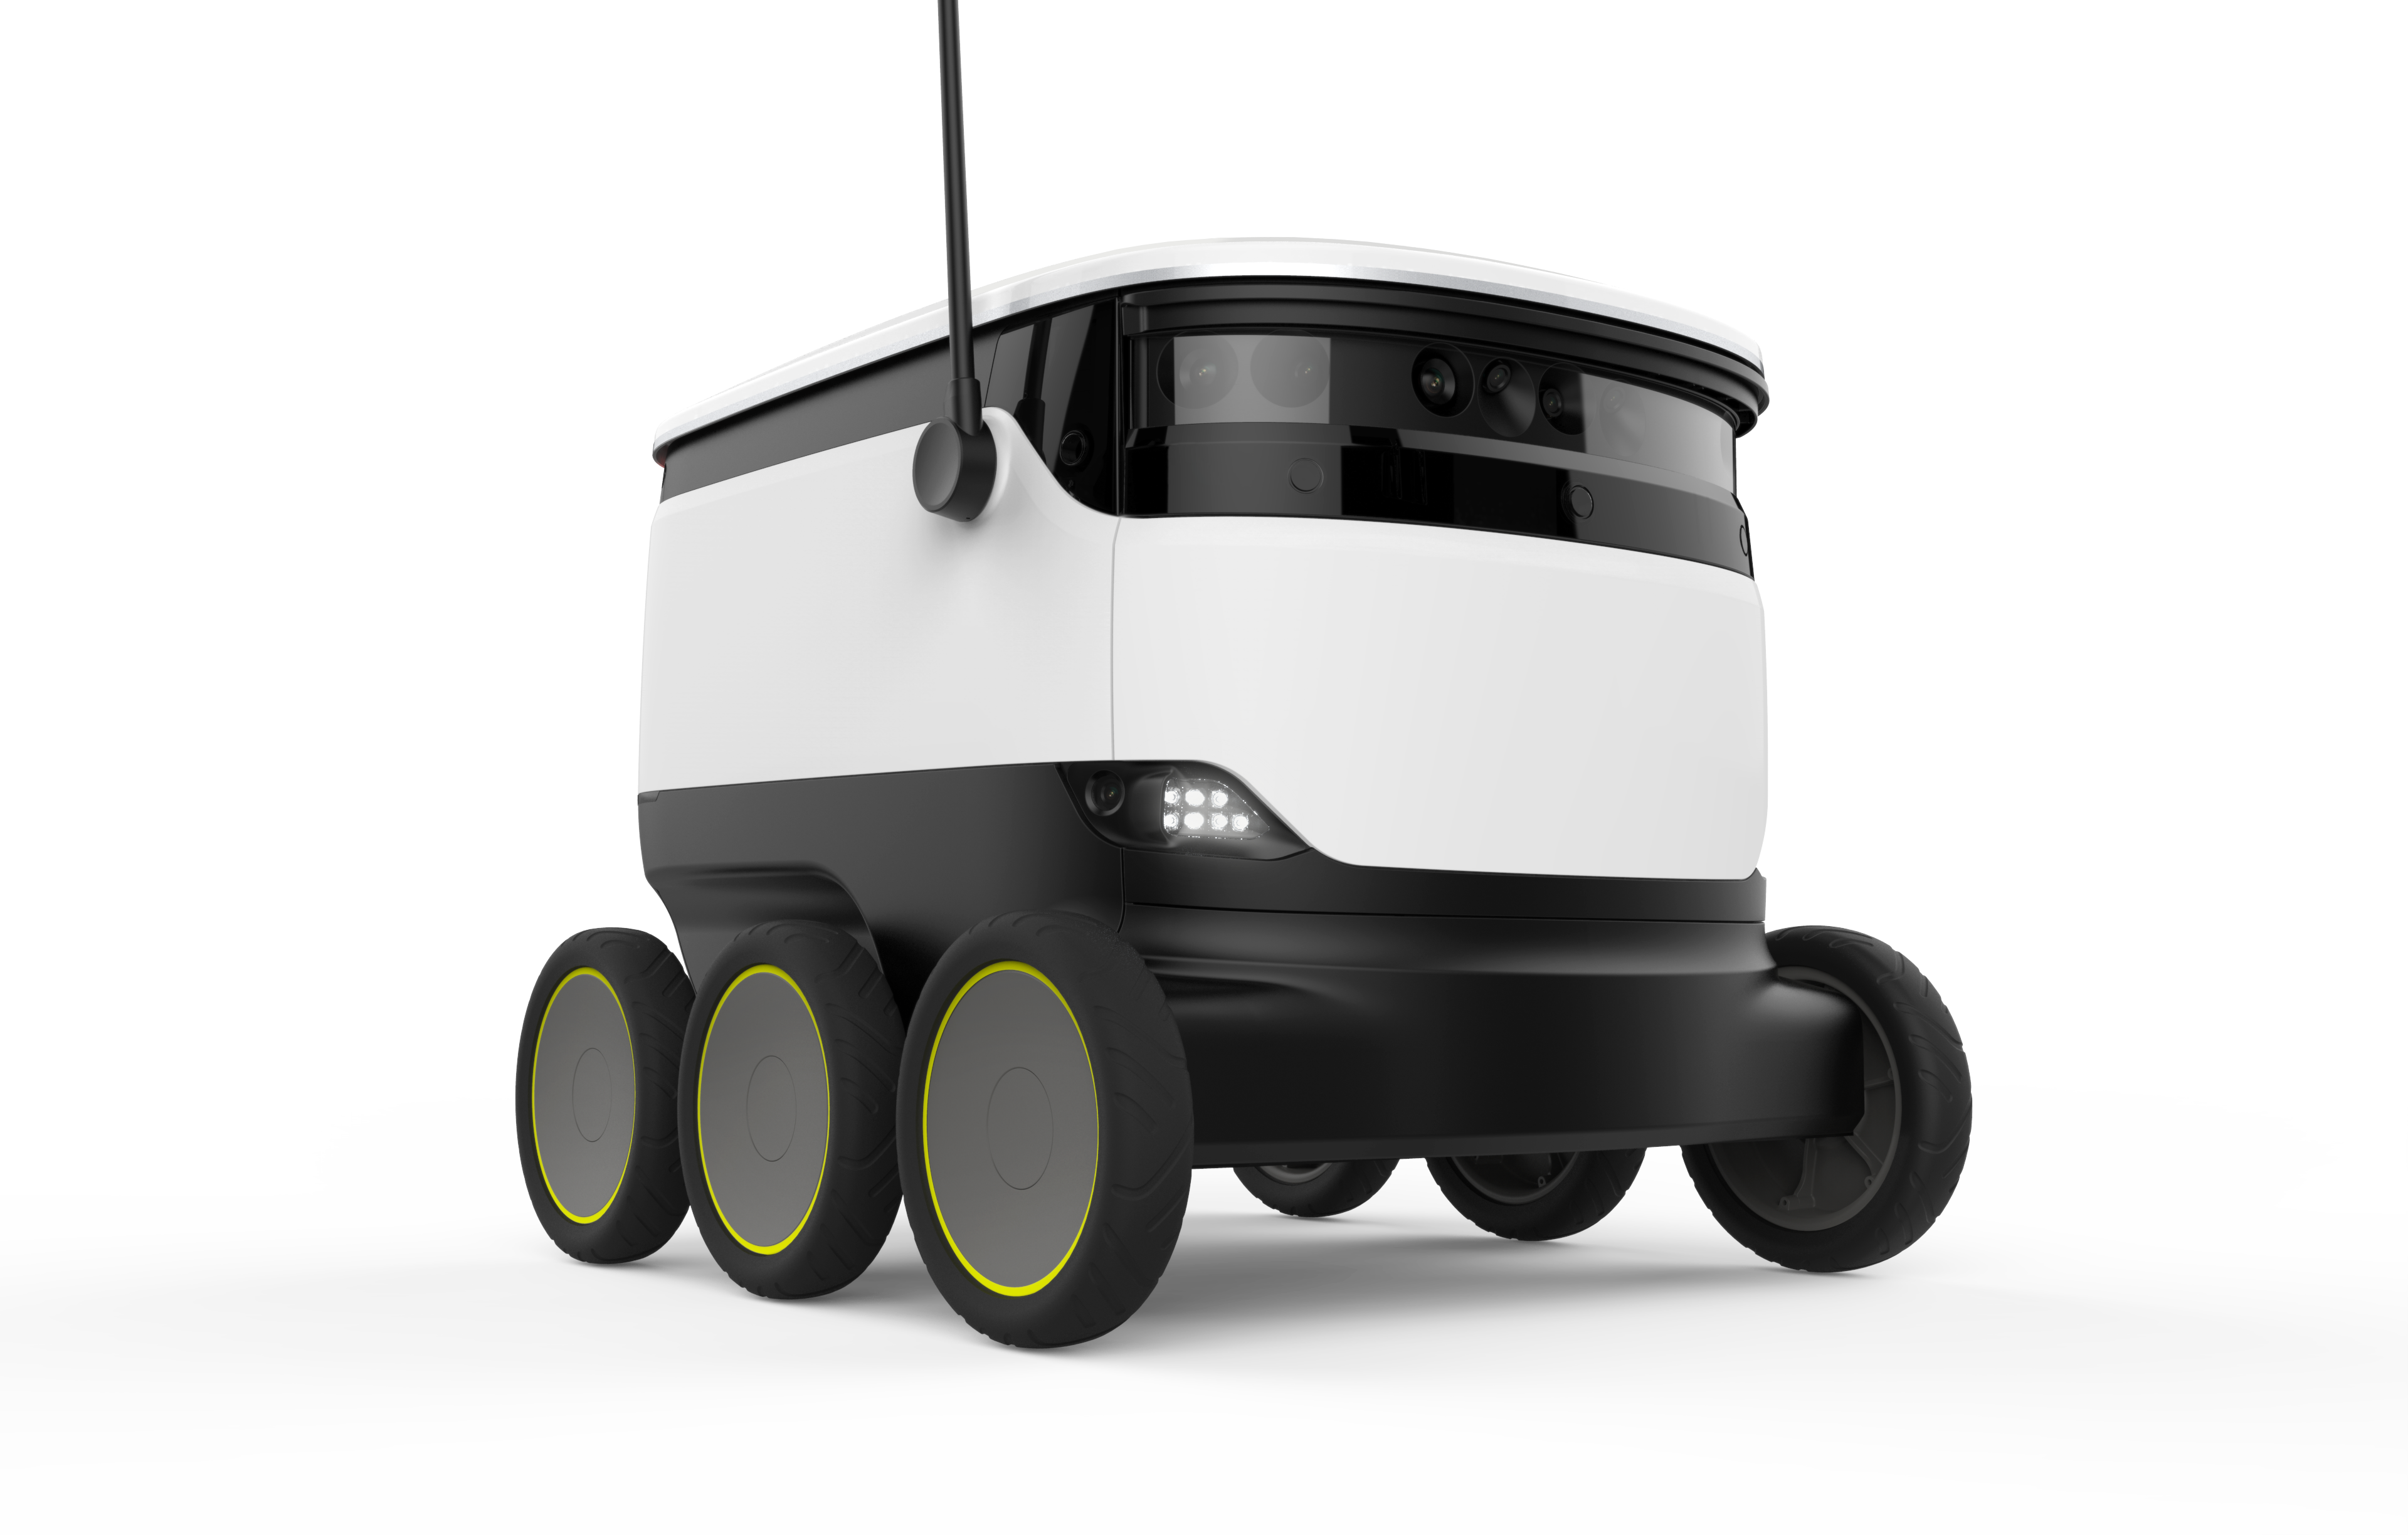
Starship Technologies has crossed 10 million autonomous deliveries, marking what may be the clearest evidence yet that sidewalk delivery robots have graduated from controlled pilots to genuine commercial infrastructure. The milestone matters beyond the headline number: it represents a measurable data point on whether Physical AI systems can operate reliably and economically at scale — the question every serious robotics buyer is asking right now.
- Why 10 Million Deliveries Is a Physical AI Benchmark
- How Sidewalk Robot Economics Compare to Traditional Last-Mile Delivery
- What Starship's Deployment Model Reveals About Scaling Autonomous Systems
- Limitations and Open Questions
- What This Means for Robotics and Automation Buyers
- Frequently Asked Questions
Why 10 Million Deliveries Is a Physical AI Benchmark
Ten million is not an arbitrary threshold. It is the kind of operational volume at which edge cases stop being edge cases — where real-world sensor noise, unpredictable pedestrian behaviour, and infrastructure inconsistencies have had to be solved at scale, not just in simulation.
According to Robotics and Automation News, Starship Technologies is describing this milestone as a turning point for physical AI systems operating in unstructured real-world environments. That framing is deliberate. Physical AI — the integration of machine learning and autonomy into systems that act on the physical world — is routinely demonstrated in labs and short pilots. Demonstrating it across 10 million real-world interactions is categorically different.
For context, most autonomous delivery pilots still operate in the hundreds or low thousands of trips. A system that has completed 10 million deliveries has encountered an estimated tens of millions of novel decision points: yielding to a cyclist, navigating a wet kerb drop, recovering from a GPS dropout in a dense urban canyon. Each solved instance feeds the model. The fleet's collective experience compounds.
This is why fleet scale matters more than individual robot capability in the current generation of Physical AI. A single highly-capable robot is impressive. A fleet of less-capable robots with shared learning, operating at 10 million-delivery scale, is infrastructure.
How Sidewalk Robot Economics Compare to Traditional Last-Mile Delivery
The economic case for autonomous sidewalk delivery has been speculative for years. At 10 million deliveries, it becomes auditable.
Traditional last-mile delivery — the leg from a local depot to a customer's door — is the most expensive segment of the logistics chain, typically accounting for 41% of total supply chain costs. Human courier costs in developed markets range from $5 to $15 per delivery once labour, vehicle, and insurance costs are fully loaded. Gig economy models have compressed that range, but not eliminated the fundamental labour dependency.
Sidewalk delivery robots change the cost structure fundamentally. The table below compares the two models across key economic dimensions:
| Cost Dimension | Human/Gig Courier | Autonomous Sidewalk Robot |
|---|---|---|
| Per-delivery labour cost | $5–$15 | Near-zero at scale |
| Fleet capital cost | Low (variable) | High upfront, depreciates |
| Operational radius | ~5 miles | ~1–2 miles (current gen) |
| Weather limitations | Moderate | Moderate–High |
| 24/7 availability | No (shift-dependent) | Yes |
| Regulatory friction | Low | Medium–High (varies by city) |
| Insurance / liability | Established | Evolving |
The economics only favour autonomous systems above a certain deployment density. Running one robot across a sparse route is expensive. Running a coordinated fleet across a dense campus or urban zone — Starship's primary deployment model — pushes per-delivery costs toward $1–$2, a figure that would represent structural disruption to gig delivery platforms if sustained.
Starship's campus and suburban deployment focus is not a limitation — it is a deliberate optimisation for the environments where the density math works.
What Starship's Deployment Model Reveals About Scaling Autonomous Systems
Starship's approach offers a usable framework for evaluating any Physical AI deployment, not just delivery robots.
The company has concentrated deployments in controlled-density environments: university campuses, corporate parks, and suburban residential zones. These are not arbitrary choices. They are environments with predictable pedestrian volumes, mapped infrastructure, and receptive regulatory environments. That combination reduces the long tail of edge cases the autonomy stack must handle, which directly reduces the cost and time of reaching reliable operation.
This is the "geofenced maturity" model: achieve near-perfect reliability within a bounded operational design domain (ODD), then expand the ODD incrementally as fleet data accumulates. It contrasts with the "full autonomy from day one" approach that has caused high-profile setbacks in autonomous vehicles.
The 10 million delivery figure suggests Starship's ODD expansion has been steady rather than explosive. The robots are not operating in every city. They are operating reliably in a growing number of specifically chosen environments — which is exactly the right signal for buyers evaluating whether a physical AI system is commercially ready.
For operators considering autonomous ground vehicles (AGVs) or mobile robots for logistics, Starship's model reinforces a key deployment principle: constrain the environment before you expand the capability.
Limitations and Open Questions
The milestone is real. The caveats are also real, and serious buyers should hold both simultaneously.
Operational radius remains narrow. Current-generation sidewalk robots operate effectively within roughly 1–2 miles of a fulfilment point. That suits campuses and dense residential zones but excludes most suburban and rural last-mile scenarios. For the majority of global parcel volume, sidewalk robots are not yet a solution.
Regulatory inconsistency is a genuine ceiling. Sidewalk robot legislation varies dramatically between cities and countries. Deployments that work legally in Milton Keynes or San Jose may face outright bans or undefined legal status elsewhere. Scaling to mainstream adoption will require regulatory frameworks to mature in parallel with the technology — a dependency the technology cannot control.
Weather performance requires scrutiny. Sidewalk robots handle light rain adequately in most reported deployments, but ice, heavy snow, and high winds remain operationally challenging. Any ROI analysis for temperate or northern climates needs to account for seasonal downtime.
The 10 million figure covers cumulative deliveries across the fleet's operational history. Fleet size, average daily delivery rate, and per-unit utilisation are more granular metrics that Starship has not publicly disclosed in detail. Buyers should request these figures before making deployment decisions.
What This Means for Robotics and Automation Buyers
For logistics operators, campus facilities managers, and last-mile delivery planners, Starship's milestone shifts the evaluation question from "does this technology work?" to "does this technology work in my specific environment?"
The evidence now supports autonomous sidewalk delivery as a viable operational choice within the right operational design domain. The key evaluation checklist:
- Deployment density: Do you have sufficient order volume within a 1–2 mile radius to drive fleet utilisation above 60–70%?
- Infrastructure quality: Are your footpaths, kerb cuts, and access points consistently navigable?
- Regulatory status: Has your city or region established a legal framework for sidewalk robots?
- Integration readiness: Does your ordering platform support API integration with an autonomous delivery fleet?
If the answer to all four is yes, the economics are compelling. If one or more is no, the deployment risk outweighs the cost advantage today — but that calculus shifts as the technology and regulatory environment mature.
For buyers evaluating broader autonomous mobile robot options for logistics and fulfilment, browse industrial and mobile robots on Robot Overflow to compare available platforms. If you are specifically evaluating collaborative or lighter-duty delivery robots, used cobots for sale on Robot Overflow includes a range of mobile manipulation and logistics platforms at various price points.