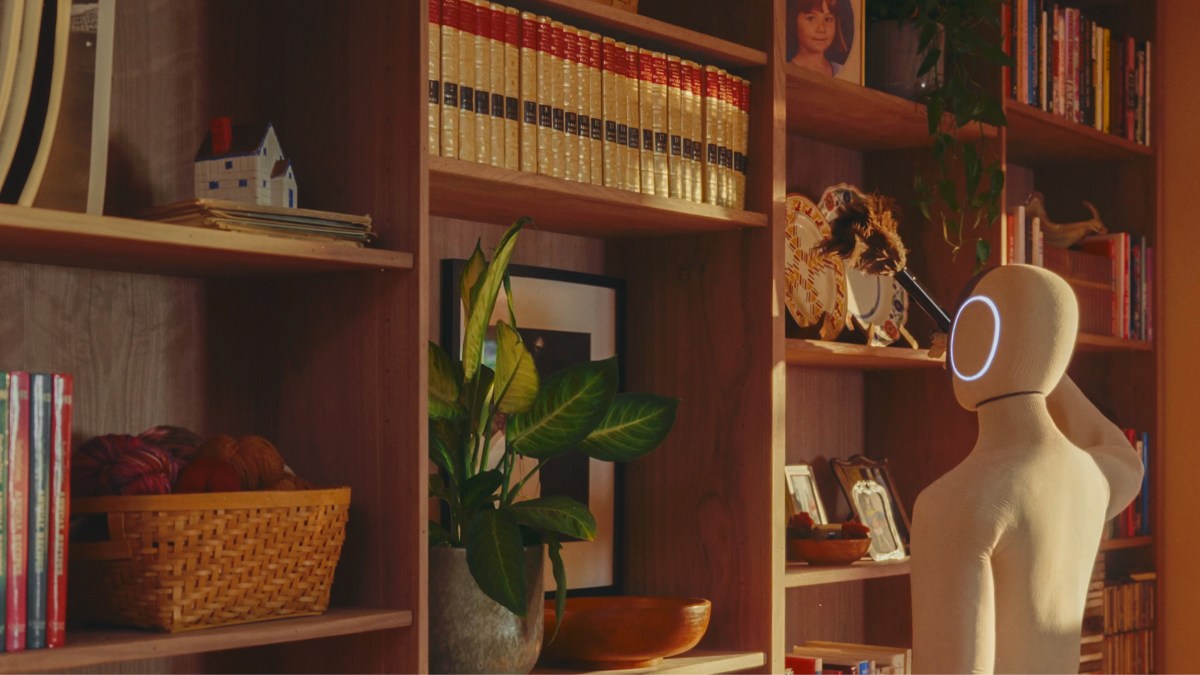
1X Technologies, the Norwegian humanoid robotics company originally targeting the consumer home market, has secured a commercial deal to deploy its Neo robots in factories and warehouses. The pivot raises a pointed question for the entire humanoid sector: is this a sign of market maturity, or evidence that the consumer humanoid market isn't ready to absorb supply?
- What Is the 1X Neo and Why Does It Matter?
- What the Industrial Deal Actually Involves
- Consumer Humanoid Demand vs. Industrial Reality
- Where 1X Stands in the Humanoid Competitive Landscape
- What This Means for Robotics Buyers and the Industry
- Frequently Asked Questions
What Is the 1X Neo and Why Does It Matter?
The 1X Neo is a full-body, wheeled humanoid robot originally designed for domestic assistance tasks — think folding laundry, fetching objects, navigating cluttered living spaces. Unlike legged humanoids such as Figure 01 or Boston Dynamics' Atlas, Neo uses a wheeled base combined with a humanoid upper body, prioritising stability and energy efficiency over bipedal locomotion.
This design choice is significant. Wheeled humanoids can operate longer between charges and navigate structured environments more reliably than legged counterparts — which makes them genuinely well-suited to warehouses and factory aisles, even if that wasn't the original pitch. 1X has positioned Neo as a platform capable of learning manipulation tasks through imitation learning, a technique where the robot learns by observing human demonstrations rather than relying on explicit programming.
The company has raised significant venture backing, including from OpenAI, lending it credibility in the "embodied AI" space where software intelligence and physical hardware converge.
What the Industrial Deal Actually Involves
According to TechCrunch, 1X has struck a commercial agreement to send Neo robots into factory and warehouse environments — a notable departure from the consumer narrative that has defined the company's public-facing identity.
The deal represents the first confirmed large-scale commercial deployment for Neo outside of 1X's own internal operations. Specific details about the partner company, the number of units involved, and the exact task scope have not been fully disclosed. What is clear is that Neo will be performing structured manipulation and logistics tasks — precisely the workflows that industrial buyers have been demanding from the humanoid sector for years.
This matters beyond 1X itself. Humanoid robots entering industrial environments need to clear a very different bar than consumer devices: uptime requirements of 95%+, integration with warehouse management systems (WMS), compliance with industrial safety standards, and measurable throughput benchmarks. If Neo performs in this environment, it validates the hardware platform far more credibly than any home pilot could.
Consumer Humanoid Demand vs. Industrial Reality
Here is the uncomfortable read on this pivot: the consumer humanoid market has consistently underdelivered on commercial traction. Despite high-profile demos and significant venture investment across the sector, no humanoid company has yet achieved meaningful consumer sales volume at scale.
The reasons are structural. Consumer humanoid deployment requires:
- In-home safety certification across varied, unstructured environments
- Price points below $20,000-30,000 to reach mainstream adoption
- Reliable general-purpose manipulation — a capability that remains genuinely hard
- Consumer support infrastructure that no humanoid company currently has at scale
Industrial environments, by contrast, offer structured layouts, defined task sets, and buyers who understand the ROI calculation. A warehouse operator asking "can this robot pick SKUs at X units per hour with Y% accuracy?" is an easier question to answer than "can this robot reliably help my elderly relative around a cluttered apartment?"
| Factor | Consumer Market | Industrial Market |
|---|---|---|
| Environment | Unstructured, variable | Structured, predictable |
| Buyer sophistication | Low | High |
| ROI clarity | Vague | Quantifiable |
| Safety certification bar | Extremely high | Established frameworks |
| Price sensitivity | Very high | Moderate |
| Current market readiness | Early / speculative | Active deployments |
The table makes the logic plain. Industrial is simply the path of least resistance for hardware that works but needs a paying customer to prove it.
That said, this shouldn't be read as pure retreat. Companies like Figure, Apptronik, Agility Robotics, and Unitree have all followed the same trajectory: build a general-purpose platform, prove it in controlled industrial environments, generate revenue, then expand outward. 1X may be following the same rational playbook rather than abandoning its consumer vision.
Where 1X Stands in the Humanoid Competitive Landscape
The humanoid robotics sector has consolidated around a small group of well-funded competitors, and 1X occupies an interesting position within it.
| Company | Robot | Primary Market | Locomotion | Reported Deployments |
|---|---|---|---|---|
| 1X Technologies | Neo | Consumer → Industrial | Wheeled | Early commercial |
| Figure AI | Figure 02 | Industrial | Bipedal | BMW partnership |
| Agility Robotics | Digit | Industrial logistics | Bipedal | Amazon pilots |
| Apptronik | Apollo | Industrial | Bipedal | Multiple pilots |
| Unitree | H1 / G1 | Research / Industrial | Bipedal | Broad distribution |
| Boston Dynamics | Atlas | Industrial R&D | Bipedal | Hyundai facilities |
1X's differentiation lies in its wheeled locomotion approach and its emphasis on learned behaviours via imitation learning. The company has been quieter than competitors about deployment timelines and volumes, which cuts both ways — it avoids overpromising, but also makes it harder to benchmark against peers.
The OpenAI investment connection is worth noting here. As large language models and vision-language models (VLMs) become more capable at reasoning about physical tasks, companies with tight AI-hardware integration pipelines stand to benefit disproportionately. If 1X has built Neo's control architecture to leverage foundation model advances, the industrial pivot could accelerate capability development faster than a purely consumer rollout would.
What This Means for Robotics Buyers and the Industry
For industrial buyers, this deal signals that the humanoid supply pipeline is beginning to reach commercial terms — not just pilot agreements. Buyers evaluating automation investments should treat this as a data point worth tracking, but not yet a mature procurement option. Neo is early-stage in industrial deployment, and the absence of disclosed performance benchmarks makes independent ROI assessment difficult at this stage.
For the broader humanoid market, 1X's pivot reinforces a pattern: the industrial sector is where humanoid robots will generate their first sustainable revenue, build operational data, and prove reliability. Consumer adoption will likely follow years later, once unit economics improve and AI capabilities make general-purpose home assistance genuinely reliable.
If you're actively evaluating humanoid platforms for logistics or light manufacturing, it's worth browsing humanoid robots on Robot Overflow to compare available units — including platforms from Unitree and others that are already shipping at commercial volumes. For buyers considering a broader automation strategy that includes cobots and industrial arms alongside humanoids, used industrial robots on Robot Overflow offer a lower-risk entry point while the humanoid sector matures.
The 1X Neo is not yet widely available through secondary market channels, and pricing details for the industrial deployment have not been disclosed publicly. As commercial deployments scale, expect more transparency on unit economics.