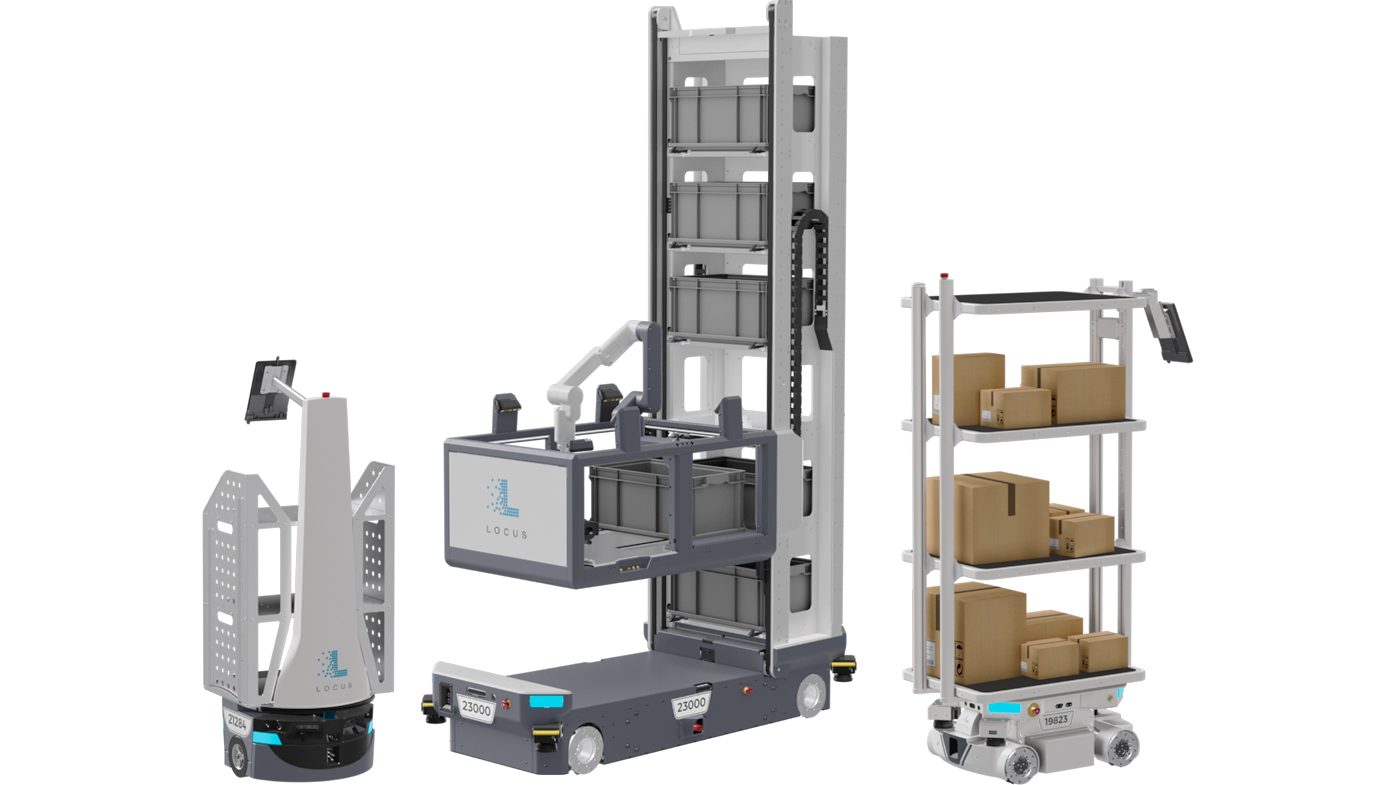
Locus Robotics has unveiled Locus Array, a fully autonomous mobile manipulation system combining an omnidirectional base, integrated picking arm, and NVIDIA-powered AI perception. Announced at MODEX, Array targets the hardest unsolved problem in warehouse automation — autonomous picking at scale — and positions Locus directly against Boston Dynamics Stretch and Berkshire Grey in the race to lights-out fulfillment.
Table of Contents
- What is Locus Array and how does it work?
- How does Locus Array compare to Boston Dynamics Stretch and Berkshire Grey?
- What is the LocusONE platform and why does it matter?
- What happens to legacy LocusBots when Array arrives?
- What This Means for Warehouse Automation Buyers
- Frequently Asked Questions
What is Locus Array and how does it work?
Locus Array is a robots-to-goods (R2G) mobile manipulation system that navigates directly to inventory within existing warehouse aisles, executes picks autonomously, and handles putaway, induction, slotting, and replenishment — all without modifying rack infrastructure or redesigning facility layouts. Locus claims it reduces manual labor by 90% and deploys in weeks rather than months.
The distinction from older automation paradigms matters here. Traditional goods-to-person (G2P) systems — think Autostore or Ocado-style grids — move inventory to a stationary worker or robot. The racks travel; the picker waits. Array inverts this: the robot travels through conventional aisles while inventory stays put. This eliminates the racking infrastructure investment that makes G2P expensive and brittle. A grid failure in an ASRS can lock SKUs in place; in Array's R2G architecture, manual picking remains possible even during a system fault.
According to The Robot Report, Locus has processed more than 7 billion picks across its fleet since founding — a volume that supplied real-world training data for Array's vision and manipulation models. CEO Rick Faulk frames this as the decisive advantage: "We're not coming out of a lab but from real-world deployments."
The system operates as part of a coordinated fleet alongside the Locus Origin (2016) and Vector (2023) AMRs (autonomous mobile robots), covering 100% of SKUs within a unified platform.
How does Locus Array compare to Boston Dynamics Stretch and Berkshire Grey?
Mobile manipulation for warehouse picking is now a crowded arena. Locus Array competes directly with Boston Dynamics Stretch, Berkshire Grey's integrated picking systems, and emerging entrants like Pickle Robot. Here's how the key systems stack up on publicly available data:
| System | Primary Task | Deployment Model | Infrastructure Change Required | Key Differentiator |
|---|---|---|---|---|
| Locus Array | Aisle picking, putaway, replenishment | RaaS (subscription) | Minimal — works with existing racks | Full workflow breadth; fleet orchestration via LocusONE |
| Boston Dynamics Stretch | Case depalletising, trailer unloading | Capital purchase / lease | Moderate — staging zones needed | High-force manipulation; proven in trailer unloading |
| Berkshire Grey | Goods-to-person induction, picking | Capital + integration | Significant — conveyance integration | High-speed sortation; vision-based bin picking |
| Pickle Robot | Case picking from shelving | RaaS | Low | Deep-SKU flexibility; long-arm reach |
The starkest contrast is scope. Stretch is purpose-built for case depalletising — moving heavy boxes from pallets to conveyors. It excels at that single task. Array claims six distinct workflow types in a single platform: picking, putaway, induction, drop-off, slotting, and replenishment. Whether real deployments validate that breadth at production throughput rates remains the key question to watch.
Berkshire Grey targets a different workflow layer — high-speed induction and sortation — rather than aisle-level picking. The competitive overlap with Array is partial, not direct.
What separates Array most clearly from the field is the RaaS (robotics-as-a-service) pricing model, which converts capital expenditure into an operational expense. For mid-market 3PLs without eight-figure automation budgets, this is structurally significant.
What is the LocusONE platform and why does it matter?
LocusONE is the AI orchestration layer that coordinates Array alongside Origin and Vector AMRs as a single unified fleet. It runs foundation models and inference at the edge on NVIDIA hardware, dynamically assigning work based on real-time demand signals rather than pre-programmed task queues.
This is where Locus is making its most aggressive technical claim. Traditional warehouse management systems (WMS) assign tasks through static rules: pick location A, deposit at station B. LocusONE's architecture treats the warehouse as a dynamic environment where task assignment, routing, and inventory slotting are continuously re-optimised. The sub-platform LocusINTELLIGENCE handles the operational analytics layer, targeting what the company calls "lowest cost per pick" — a metric that compounds in significance at billion-pick scale.
Edge inference matters here because latency kills picking throughput. A robot arm waiting 200 milliseconds for a cloud round-trip on every grasp attempt loses meaningful productivity at scale. Running vision models locally on NVIDIA hardware means perception decisions happen in the aisle, not in a data centre.
The physical AI framing Faulk uses — "Array can perceive, reason, and act" — maps onto the embodied AI terminology gaining traction in robotics research. The meaningful test is generalisation: can Array's vision system handle novel SKUs, damaged packaging, or partial occlusion without human intervention? Locus's 7 billion pick training corpus suggests the models have seen more edge cases than most competitors, but independent throughput benchmarks on mixed-SKU assortments haven't yet been published.
What happens to legacy LocusBots when Array arrives?
Array's launch raises a practical question for the 350+ facilities already running Locus Origin and Vector fleets: does the new system obsolete existing hardware?
The answer, by design, is no — but the market dynamics are more complicated. Locus has explicitly positioned Array as an addition to the fleet, not a replacement. Origin and Vector handle tasks Array doesn't: high-speed transport between zones, human-collaborative picking where a worker selects items and a bot carries the tote. Array handles fully autonomous picking where human labour is being removed from the loop entirely.
For buyers evaluating secondary market options, this creates an interesting window. As customer sites upgrade to Array for their highest-value picking workflows, Origin and Vector units may migrate to lower-intensity tasks or enter the secondary market. For operations that need AMR transport capacity without the mobile manipulation premium, used Locus Origin or Vector robots represent a cost-effective entry point into the Locus ecosystem.
DHL Supply Chain's trajectory is instructive. After completing 1 billion picks with existing Locus systems, DHL deployed Array at its first Columbus, Ohio site — and logged 21 million additional picks in the weeks immediately following the announcement. That's a fleet expansion story, not a rip-and-replace.
What This Means for Warehouse Automation Buyers
Locus Array's global launch marks a maturation point for mobile manipulation: the technology is moving from pilot programmes to production deployments at named enterprise accounts. For buyers evaluating warehouse automation investments in 2025-2026, the decision framework has shifted.
If you're running a mid-size 3PL or e-commerce fulfilment operation, Array's RaaS model removes the capital barrier that previously made mobile manipulation inaccessible. The deployment-in-weeks claim — versus months for ASRS or goods-to-person systems — also reduces operational risk during transition.
If you already operate a Locus fleet, the fleet compatibility story means Array can be added incrementally to your highest-labour-cost workflows without displacing existing automation investment.
If you're evaluating competitors, the comparison table above frames the workflow scope question clearly. Array's breadth claim needs validation in your specific SKU mix and facility layout before purchase commitment.
For operations exploring used industrial robots as a cost-efficient path into automation, or those considering a first move into used cobots for sale before committing to a full mobile manipulation deployment, the secondary market now includes an expanding pool of proven AMR hardware as fleets upgrade.
The lights-out warehouse — fully autonomous, 24/7, zero-touch fulfilment — remains a horizon target rather than an immediate reality for most operations. Array moves that horizon measurably closer.