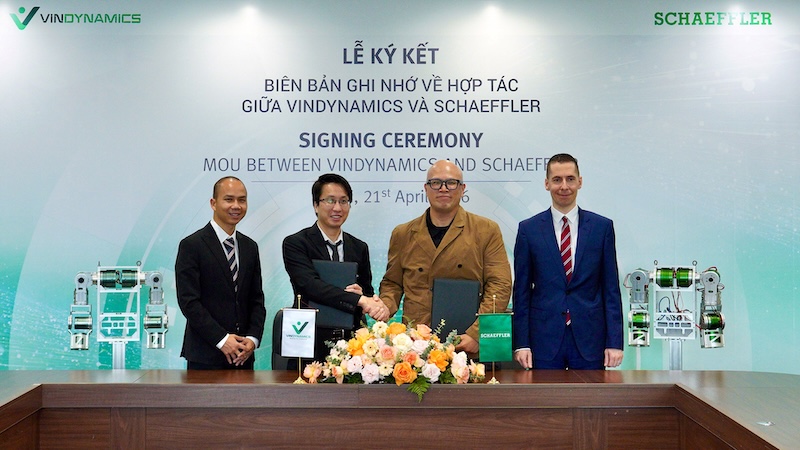
German precision engineering giant Schaeffler has formed a strategic partnership with VinDynamics — the humanoid robotics arm of Vietnam's Vingroup — to co-develop and supply planetary gearboxes for humanoid robot actuators. The deal pulls back the curtain on a critical but under-discussed supply chain question: who actually builds the mechanical joints that let humanoid robots walk, grasp, and lift?
- Why Planetary Gearboxes Are the Hidden Bottleneck in Humanoid Robotics
- Who Is VinDynamics and Why Does This Partnership Matter?
- Who Else Supplies Actuator Components to the Humanoid Industry?
- What This Means for Robotics
- Frequently Asked Questions
Why Planetary Gearboxes Are the Hidden Bottleneck in Humanoid Robotics
Most humanoid robot coverage focuses on AI, software stacks, or flashy demos. The mechanical reality is less glamorous but more constraining: without high-precision, compact gearboxes capable of handling repeated dynamic loads, a humanoid's joints fail, overheat, or lose positional accuracy within hours of real-world use.
A planetary gearbox — named for the way smaller "planet" gears orbit a central "sun" gear inside a fixed outer ring — is the standard transmission mechanism used inside robotic actuators (the motorised joint assemblies that function as a humanoid's muscles). They are preferred over simpler gearbox designs because they distribute load across multiple gear contacts simultaneously, achieving high torque density in a compact form factor. Think of it as the difference between a single load-bearing column and a Roman arch: the distributed structure handles far more stress.
Where the analogy breaks down: unlike a static arch, planetary gearboxes in humanoid joints must handle millions of bidirectional cycles, rapid acceleration, and varying payloads — all while maintaining sub-millimetre positional repeatability. That combination of requirements is extraordinarily difficult to manufacture at scale.
This is precisely why the Schaeffler-VinDynamics agreement is significant. Schaeffler brings over 75 years of precision bearing and transmission manufacturing experience — its components already appear inside automotive drivetrains, aerospace systems, and industrial machinery worldwide. Applying that manufacturing depth to humanoid-specific gearbox geometry is not a trivial extension of existing capability.
Who Is VinDynamics and Why Does This Partnership Matter?
VinDynamics is a relatively new entrant to the humanoid robotics space, operating under Vietnam's Vingroup — a conglomerate with revenues exceeding $12 billion and significant investments in electric vehicles (VinFast), healthcare, and smart cities. The robotics division represents Vingroup's push into physical automation technology, positioning Vietnam as more than an electronics assembly hub.
According to Robotics and Automation News, the partnership extends beyond component supply. The two companies will also conduct joint development work, suggesting Schaeffler is not simply acting as a tier-one supplier but is collaborating on gearbox architecture optimised for VinDynamics' specific robot platform.
This structure mirrors a broader pattern in the humanoid industry: robot OEMs (original equipment manufacturers) increasingly forming deep engineering partnerships with established precision component suppliers rather than attempting vertical integration from day one. The technical barriers to in-house gearbox development — specialised metrology, heat treatment processes, and gear grinding equipment — are prohibitive for most robotics startups operating on compressed timelines.
For VinDynamics, access to Schaeffler's manufacturing infrastructure and institutional knowledge dramatically compresses development time. For Schaeffler, the deal opens a growth vector in a market that analysts project could require millions of actuator assemblies annually within the coming decade as humanoid deployments scale.
Who Else Supplies Actuator Components to the Humanoid Industry?
The Schaeffler-VinDynamics deal is one node in an emerging supplier ecosystem that most industry observers haven't fully mapped. Here's how the actuator component landscape currently looks:
| Supplier | Origin | Component Focus | Known Humanoid Customers |
|---|---|---|---|
| Schaeffler | Germany | Planetary gearboxes, bearings | VinDynamics (announced) |
| Harmonic Drive | Japan/USA | Strain wave gearboxes | Widely used across industry |
| Nabtesco | Japan | Cycloidal gearboxes | Industrial and humanoid |
| HEBI Robotics | USA | Modular actuator modules | Research platforms |
| Maxon Motor | Switzerland | Precision DC motors + gearheads | Boston Dynamics, others |
| Wittenstein | Germany | Planetary and servo gearboxes | Industrial cobots, humanoids |
Each gearbox architecture involves trade-offs that matter enormously at the joint level. Strain wave gearboxes (Harmonic Drive's signature product) offer near-zero backlash and high torque in a thin profile — ideal for wrist and finger joints — but are less efficient under continuous high-load conditions. Cycloidal gearboxes handle shock loads extremely well, making them suited for ankle and hip joints that absorb impact during locomotion. Planetary gearboxes, as Schaeffler is pursuing with VinDynamics, sit between these extremes: highly efficient, scalable to manufacture, and versatile across joint types.
The dominance of Japanese suppliers — particularly Harmonic Drive — in the current humanoid supply chain is a geopolitical and commercial risk that multiple humanoid OEMs are actively trying to diversify away from. European precision manufacturers like Schaeffler and Wittenstein are the natural beneficiaries of that diversification pressure.
For buyers evaluating humanoid robots on the market, gearbox supplier lineage is rarely disclosed in product datasheets — yet it is one of the most consequential factors determining long-term joint reliability and maintenance cost.
What This Means for Robotics
The Schaeffler-VinDynamics partnership is a bellwether for how the humanoid supply chain is regionalising and professionalising simultaneously. Several implications stand out for buyers, engineers, and investors tracking this space.
Supply chain diversification is accelerating. The concentration of precision gearbox manufacturing in Japan has been a known fragility. European entrants like Schaeffler bring manufacturing quality comparable to Japanese incumbents, with different geopolitical risk exposure. Expect more of these cross-continental partnerships as humanoid OEMs build redundancy into their supply chains.
Vietnam is becoming a serious robotics manufacturing node. VinDynamics is not a lone outlier — it reflects Vingroup's calculated bet that Vietnam's manufacturing cost advantages, combined with aggressive technology investment, can position the country as a humanoid robot producer rather than just an assembler. If VinDynamics' platform reaches commercial scale, the Schaeffler relationship gives it credible component pedigree.
The actuator cost problem remains unsolved. Current high-performance gearboxes from established suppliers cost hundreds to low thousands of dollars per unit — and a single humanoid requires dozens of actuated joints. Until gearbox manufacturing achieves the economies of scale seen in automotive transmissions, actuator costs will remain the primary barrier to sub-$30,000 humanoid pricing. Partnerships like this one are a step toward that scale, not an arrival at it.
For buyers of industrial and collaborative robots today, this dynamic reinforces a practical point: the mechanical drivetrain — not just the AI stack — determines the total cost of ownership of any robot system. Ask suppliers about gearbox sourcing, expected service intervals, and replacement part availability before committing to a platform.