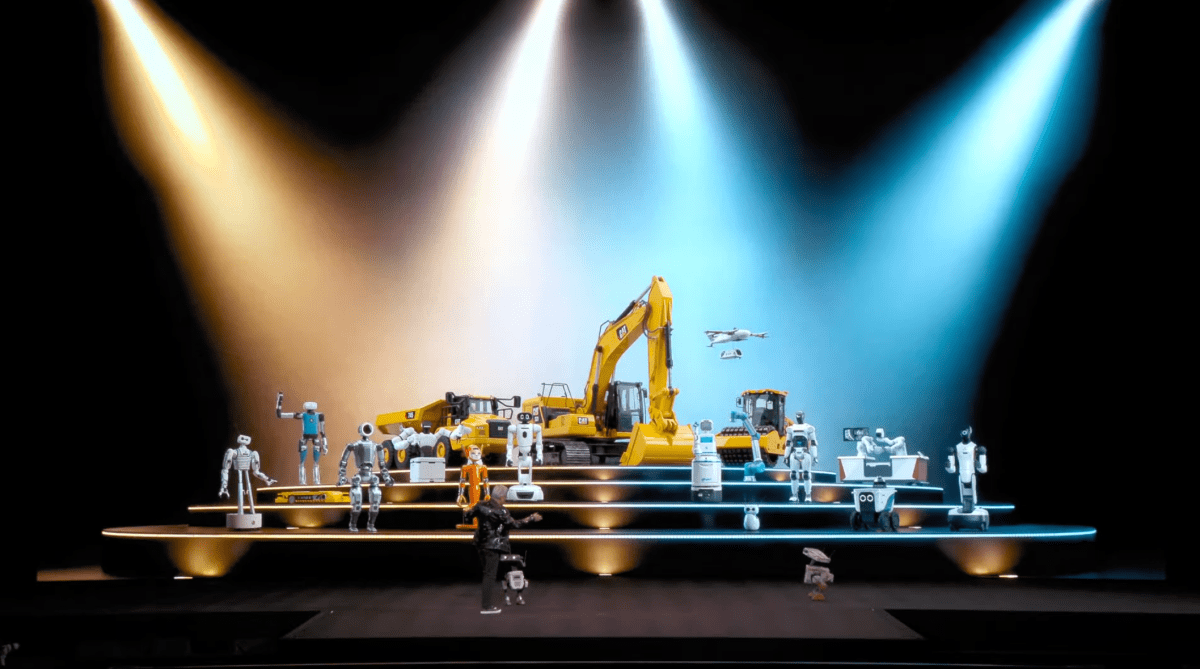
After years of software-only AI dominance, the Las Vegas convention floor just delivered its clearest signal yet: the physical AI era has arrived. CES was overrun with humanoid robots, AI-integrated hardware, and embodied intelligence systems — from Boston Dynamics' redesigned Atlas to AI-powered appliances — marking the moment robotics moved from industry curiosity to mainstream technology story.
- What Is Physical AI and Why Did It Dominate CES?
- Boston Dynamics Atlas: What the Redesign Actually Signals
- The Spectrum: From Humanoids to AI Ice Makers
- How CES Buzz Translates to Secondary Market Valuations
- What This Means for Robotics Buyers
- Frequently Asked Questions
What Is Physical AI and Why Did It Dominate CES?
Physical AI refers to artificial intelligence systems embedded in hardware that perceives and acts on the real world — robots, autonomous vehicles, smart appliances, and any machine that moves or manipulates its environment using learned intelligence. Unlike language models or image generators, physical AI must contend with physics, uncertainty, and real-time feedback loops. CES became its defining showcase because the technology has finally reached commercial readiness across multiple price tiers simultaneously.
The terminology itself is telling. "Physical AI" is not an academic category — it's an industry positioning move. NVIDIA's Jensen Huang popularised the framing, and by CES it had been adopted wholesale by exhibitors ranging from Boston Dynamics down to consumer appliance brands. When a convention's entire narrative collapses around a single phrase, it usually means something real is happening underneath the marketing.
The underlying driver is convergence. Three capabilities — large-scale foundation models for perception and planning, affordable actuator hardware, and fast simulation environments for training — have matured enough to combine into commercially viable products. That convergence is what made CES feel different from previous years, where robotics was confined to a single hall and treated as a novelty category.
Boston Dynamics Atlas: What the Redesign Actually Signals
The newly redesigned Atlas humanoid represents Boston Dynamics' clearest commercial pivot to date — a shift from demonstration platform to deployable industrial asset. The electric Atlas replaces the hydraulic research system, prioritising reliability, repairability, and software integration over raw athletic performance.
This distinction matters enormously for buyers and for the secondary market. The hydraulic Atlas was a research instrument; spectacular on video, impractical to operate at scale. The electric redesign signals that Boston Dynamics — now backed by Hyundai — is targeting real manufacturing and logistics environments. Hyundai has explicitly committed to deploying Atlas units in its own production facilities, which creates a reference deployment pipeline that builds buyer confidence.
Key changes in the redesigned Atlas include:
| Feature | Hydraulic Atlas (prior gen) | Electric Atlas (current gen) |
|---|---|---|
| Actuation type | Hydraulic | Electric motors |
| Primary use case | Research / demonstration | Industrial deployment |
| Degrees of freedom | ~28 DoF | Reconfigured for task flexibility |
| Operational focus | Athletic performance | Reliability and integration |
| Commercial availability | Limited research sales | Hyundai facility rollout |
The CES showing confirms that Atlas is being positioned not as a product you buy today at a consumer price point, but as a platform entering structured commercial deployment. That distinction shapes how secondary market pricing develops around it.
The Spectrum: From Humanoids to AI Ice Makers
CES revealed that physical AI is not a monolithic category — it's a spectrum stretching from $200,000+ industrial humanoids down to consumer appliances adding computer vision and on-device inference to mundane tasks.
At the high end, humanoid robots from multiple vendors competed for attention alongside Atlas. These systems target warehouse picking, manufacturing assembly, and inspection tasks — environments where labour is expensive, repetitive, and physically demanding. The competitive intensity at this end of the market is accelerating: according to TechCrunch's CES coverage, humanoids were among the defining visual statements of the entire show.
At the consumer end, AI integration into household hardware — ice makers, kitchen appliances, home robots — signals that the underlying technology stack is cheap enough to commoditise. This matters for the broader robotics market because:
- Component costs fall faster when consumer volumes drive semiconductor and actuator production
- Developer ecosystems grow as consumer hardware creates accessible training ground for physical AI skills
- Public familiarity increases, reducing the adoption friction that has historically slowed enterprise robotics deployments
The risk is dilution. When every appliance claims to be "AI-powered," the term loses its signal value. The robotics industry's challenge is maintaining meaningful differentiation between genuine embodied intelligence and feature-marketing dressed in AI vocabulary.
How CES Buzz Translates to Secondary Market Valuations
Major robotics showcase events reliably trigger secondary market activity — and CES is the most powerful trigger of all. When a platform receives significant press attention, two things happen simultaneously: demand inquiries spike from buyers who didn't previously consider the technology, and existing owners recalibrate their asking prices upward.
For Atlas specifically, the secondary market dynamics are unusual. Unlike cobots such as the Universal Robots UR series — which have deep, liquid secondary markets with well-established pricing — Atlas units are rare. Research-grade hydraulic Atlas robots that do appear for resale command prices reflecting both their scarcity and their status as engineering reference systems. Electric Atlas commercial units, as they enter Hyundai's deployment pipeline, will eventually generate a secondary market, but that's a multi-year horizon.
Broader physical AI secondary market trends currently observed:
| Robot Category | Secondary Market Depth | Price Trend Post-CES | Typical Use Case |
|---|---|---|---|
| Industrial humanoids (Atlas class) | Thin / specialist | Upward pressure | Manufacturing, inspection |
| Collaborative robots (UR, Fanuc) | Deep / liquid | Stable | Assembly, packaging |
| Mobile inspection robots (Spot) | Moderate | Stable-to-rising | Infrastructure, energy |
| Consumer / prosumer robots | Growing | Volatile | Education, research |
For buyers considering used industrial robots or used cobots for sale, the practical implication is clear: post-CES windows are when sellers are most active and when pricing can be either advantageous or inflated depending on category. Liquid categories like cobots offer genuine buying opportunities; headline categories like humanoids require patience and specialist sourcing.
What This Means for Robotics Buyers
CES confirms what forward-looking procurement teams have suspected: physical AI is no longer a future-state technology. Budgeting cycles that previously deferred robotics investment to a "wait and see" posture are now running out of time. The companies deploying humanoids and advanced cobots today are building operational experience that compounds over time.
Practical guidance by buyer segment:
- Industrial manufacturers: The Atlas commercial deployment at Hyundai is the reference case to watch. If your facility profile matches automotive-scale assembly or materials handling, a structured evaluation of humanoid platforms is now warranted — not as pilots, but as capital planning exercises.
- Logistics and warehousing: Mobile manipulation and autonomous mobile robots (AMRs) shown at CES represent the most near-term deployable category. Secondary market availability for proven platforms is strong, and ROI timelines are well-established.
- Research institutions and developers: CES signals that the physical AI software stack — foundation models for manipulation, vision-language-action models — is advancing rapidly. Hardware investment decisions should account for software compatibility, not just mechanical capability.
- SMEs and integrators: The consumerisation of physical AI means capable platforms are entering the market at increasingly accessible price points. The cobot secondary market in particular offers strong value for facilities not yet ready for humanoid-scale investment.