Zebra Technologies has divested its Fetch Robotics division — acquired for roughly $300 million — to Pittsburgh-based Physical AI developer Skild AI, marking one of the cleaner post-mortems of the enterprise AMR acquisition wave. Skild's platform-agnostic "Brain" now controls the full hardware stack, and the implications for AMR buyers and the used robot market are significant.
- Why Zebra Bought Fetch — and Why It Didn't Work
- What Skild AI's Omni-Bodied Brain Actually Does
- The End-to-End Warehouse Vision Skild Is Betting On
- What This Means for the Used AMR Market
- What This Means for Robotics Buyers
- Frequently Asked Questions
Why Zebra Bought Fetch — and Why It Didn't Work
Zebra Technologies spent approximately $300 million on Fetch Robotics, and five years later walked away with an equity stake in exchange. That gap between acquisition price and exit terms — undisclosed, but clearly not a premium — tells the story without needing a press release.
The acquisition logic made sense at the time. Fetch was a credible AMR player with solid warehouse deployments, and Zebra had existing distribution into logistics operations via its barcode, RFID, and mobile computing portfolio. The thesis: bundle AMRs with Zebra's workflow software and sell it all to the same supply chain buyers already running Zebra scanners.
The problem was structural. AMR hardware is capital-intensive, margin-thin, and operationally complex to support at scale. It pulled Zebra away from its core competency in enterprise data-capture — a high-margin, software-driven business. According to DC Velocity, Zebra had signalled its intent to offload the unit over the preceding six months, eventually citing a desire to "sharpen its strategic focus" on RFID, machine vision, and frontline AI.
This isn't an isolated failure of execution. It reflects a broader pattern: enterprise IT companies acquiring robotics hardware divisions and discovering that robots don't behave like software subscriptions. The AMR market rewards specialists, not aggregators.
What Skild AI's Omni-Bodied Brain Actually Does
Skild AI's core differentiator is its Skild Brain — a generalised robot intelligence platform that doesn't need to be trained or tuned for a specific robot form factor. The company describes it as "omni-bodied": give it a new robot body and it can begin controlling it without prior knowledge of that robot's kinematics or morphology.
This is a meaningful technical claim, and worth unpacking. Most robot control software is tightly coupled to specific hardware — a navigation stack written for a wheeled AMR won't transfer to a robotic arm or a quadruped without substantial re-engineering. Skild Brain's architecture is designed to abstract away from body form entirely, operating at a higher representational level closer to how reinforcement learning and foundation models approach generalisation.
The analogy is to a large language model that can reason across domains without being retrained per topic. The parallel works up to a point: where LLMs operate purely in token space, embodied AI must also contend with real-world physics, sensor noise, and actuation latency — constraints that don't exist in language models. But the ambition is similar: one general intelligence layer across many physical systems.
Skild's acquisition of the Fetch AMR fleet and Zebra's Symmetry Fulfillment orchestration platform gives the company real hardware and real deployments to prove this claim in production.
The End-to-End Warehouse Vision Skild Is Betting On
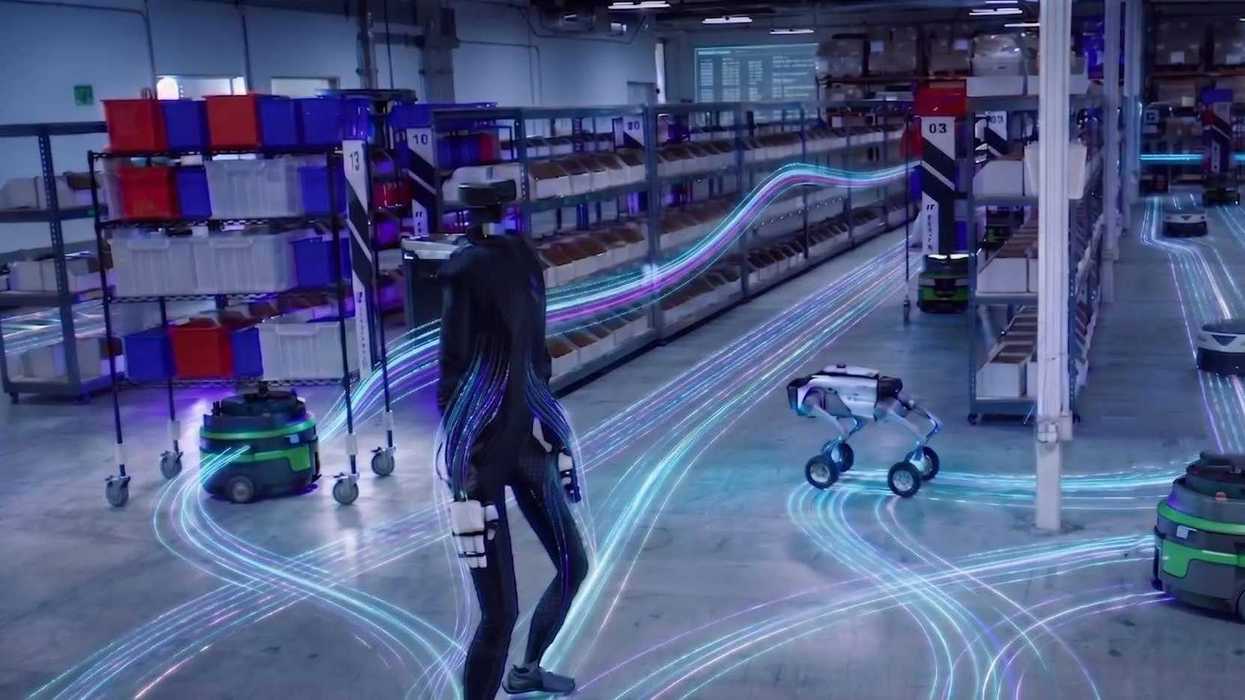
Skild AI's stated vision is ambitious: the first single organisation capable of delivering a complete, multi-robot automation solution for warehouses. That means humanoids for pick-and-place, robotic dogs for inspection, robotic arms for packing, AMRs for material movement — all coordinated by a single orchestration layer.
| Robot Type | Task | Platform Component |
|---|---|---|
| Humanoid robots | Pick-and-place fulfilment | Skild Brain (general control) |
| Robotic dogs (quadrupeds) | Facility inspection | Skild Brain (omni-bodied) |
| Robotic arms | Packing and manipulation | Skild Brain (general control) |
| AMRs (Fetch fleet) | Material transport | Zebra Symmetry orchestration |
| Frontline workers | Exception handling | Zebra wearable devices |
The orchestration layer is the piece most buyers underestimate. Individual robots solving individual tasks is a solved problem at many sites. Coordinating heterogeneous fleets — different vendors, different kinematics, different communication protocols — is where deployments break down. Zebra's Symmetry platform already handled human-robot task coordination using Zebra wearables; Skild's intent is to extend that to a fully mixed fleet of robot types.
If Skild Brain delivers on its omni-bodied promise, this architecture could eliminate the integration tax that currently forces large operators to manage multiple vendor relationships, multiple software contracts, and multiple support SLAs just to run a single fulfilment operation.
What This Means for the Used AMR Market
Corporate divestitures of robotics divisions don't just reshuffle ownership — they generate hardware. When Zebra's Fetch fleet transitions to Skild AI's portfolio, some of that installed base will be upgraded, some retained, and some released into the secondary market.
For buyers watching the used industrial robot market, this is worth tracking. Fetch AMRs — particularly the Freight series — are capable, well-documented platforms that appear regularly on the secondary market. A technology transition at the ownership level often accelerates the release of older hardware as the new owner standardises on current-generation equipment.
The more consequential shift, however, is what Skild Brain implies for used AMR value. If a general-purpose intelligence platform can be loaded onto existing Fetch hardware, those units gain a capability upgrade path without physical replacement. That changes the depreciation logic for AMRs — a used Fetch with Skild Brain compatibility is potentially worth more than a used Fetch without it. Platform stickiness, not hardware specs, becomes the primary value driver.
What This Means for Robotics Buyers
For operations managers evaluating warehouse automation, the Zebra-to-Skild transition signals something specific: vendor consolidation is accelerating, and the integration layer is becoming the product.
Buyers who have held off on AMR investment due to integration complexity now have a credible end-to-end vendor argument to evaluate. The risk is that Skild AI's omni-bodied claims remain unproven at the scale that major 3PLs and e-commerce fulfilment centres operate. Buying into a platform vision before it's validated in production is a different risk profile than buying a point solution from an established AMR specialist.
For teams ready to move now, used cobots and AMRs on Robot Overflow represent lower-risk entry points while the Physical AI platform market matures. Hardware quality from established vendors like Fetch doesn't depreciate as fast as the software layer above it evolves.
The Skild acquisition is a bet on Physical AI as the unifying layer across robot types. If that bet lands, buyers who've already deployed compatible hardware will benefit from compounding capability upgrades. If it stalls, they still have functional AMRs.