Robotaxis have crossed the threshold from cautious pilot programs to commercial-scale deployment — and the reason is a fundamental shift in AI architecture. Waymo now completes over 150,000 paid rides per week across multiple U.S. cities, while Amazon's Zoox is preparing public launches. The AI stacks enabling this leap are the same families of models reshaping embodied robotics across every industry.
- From Prototype to Platform: What Changed in the AI Stack
- How Waymo and Zoox Build Their Perception and Decision Systems
- The Hardware Economy Behind Autonomous Fleets
- Global Expansion and the Competitive Landscape
- What This Means for Robotics
- Frequently Asked Questions
From Prototype to Platform: What Changed in the AI Stack
For most of the last decade, autonomous vehicles could handle controlled environments but collapsed under edge cases — the unpredictable scenarios that make real-world driving hard. The breakthrough wasn't a single model. It was the convergence of transformer-based perception, large-scale simulation training, and onboard compute dense enough to run inference in real time.
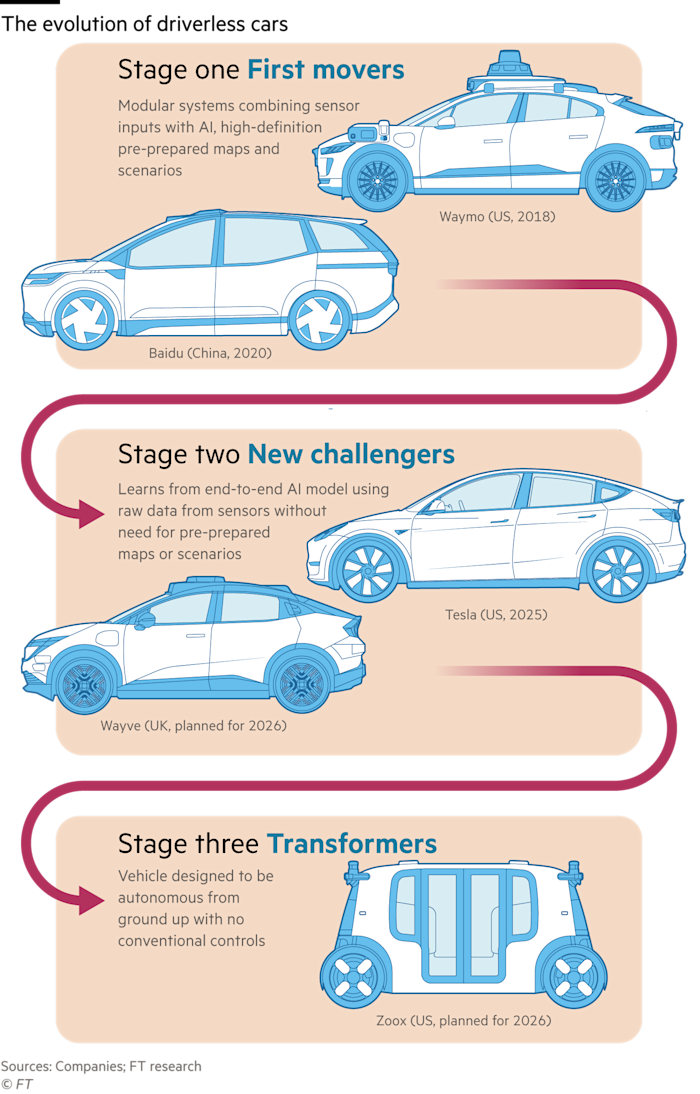
Early self-driving systems relied heavily on hand-coded rules and HD map dependency. If the map was wrong — a road closure, a new lane marking — the vehicle hesitated or failed. The shift to end-to-end learned driving models, where neural networks process raw sensor data and output driving decisions with minimal intermediate rule layers, is what unlocked genuine scalability.
Think of it like the difference between a chess engine programmed with explicit rules versus AlphaZero learning chess from scratch through self-play. Both play chess, but only one generalises to novel positions it has never encountered. The analogy breaks down because driving involves physical safety constraints that pure game-play doesn't — but the architectural principle holds.
| Approach | Map Dependency | Edge Case Handling | Scalability |
|---|---|---|---|
| Rule-based systems | High — fails off-map | Poor | Low |
| Modular ML pipelines | Medium | Moderate | Medium |
| End-to-end neural driving | Low | Strong | High |
| Hybrid (current leaders) | Low-medium | Strong | High |
This architectural maturation is precisely why robotaxi deployments are accelerating now, rather than five years ago.
How Waymo and Zoox Build Their Perception and Decision Systems
Waymo and Zoox represent two distinct philosophies in autonomous vehicle AI — and both are instructive for anyone watching the broader embodied AI space.
Waymo's approach centres on its in-house Waymo Driver stack, which fuses data from LiDAR, cameras, and radar through a proprietary perception system trained on billions of miles of real-world and simulated driving. Its recent fifth-generation hardware platform consolidates sensor processing onto custom compute modules, reducing latency and system complexity. Critically, Waymo has invested heavily in closed-loop simulation — a training paradigm where the AI drives through synthetic recreations of difficult real-world scenarios, learning from failure without physical risk.
Zoox, operating under Amazon, took a different industrial bet: it designed a bidirectional vehicle from scratch, with no steering wheel and seating facing inward. This meant building an AI stack that couldn't inherit assumptions from conventional vehicle architecture. Zoox's system handles 360-degree responsibility — there is no "front" of the car in the traditional sense — which forced a fundamentally symmetrical sensor and decision framework.
Both companies use variants of transformer architectures (the same class of model underlying large language models) for scene understanding — processing sequences of sensor frames to predict how pedestrians, cyclists, and other vehicles will behave. This temporal reasoning capability, understanding not just where objects are but where they are going, is the component that most directly parallels advances in humanoid robot motion planning.
The Hardware Economy Behind Autonomous Fleets
The robotaxi boom is generating a significant secondary market in the hardware components that make autonomous vehicles function — and this is where the story intersects directly with the broader robotics industry.
Each Waymo vehicle carries an estimated $100,000–$150,000 in sensor and compute hardware at current production costs, though the company is actively driving this figure down. The sensor suite typically includes:
- Multiple LiDAR units (for 3D point cloud mapping of the environment)
- High-resolution cameras (for colour, texture, and semantic understanding)
- Radar arrays (for velocity measurement and adverse weather resilience)
- Custom AI inference chips (for running perception and planning models at low latency)
The push to reduce per-vehicle hardware cost is driving innovation in solid-state LiDAR — a form factor with no moving parts, lower cost, and higher durability — and in domain-specific AI accelerators (chips designed specifically to run neural network inference efficiently). These same components are flowing into industrial robots, warehouse automation systems, and humanoid platforms.
NVIDIA's Drive platform and Orin SoC (system-on-chip) appear across multiple robotaxi programs, and the same silicon is increasingly specified in autonomous mobile robots (AMRs) navigating factory floors. The supply chain for robotaxi hardware and the supply chain for industrial robotics are converging — a trend that will compress costs across both sectors simultaneously.
Global Expansion and the Competitive Landscape
The competitive map has shifted considerably, with distinct regional leaders emerging.
In the United States, Waymo holds a commanding operational lead, having accumulated more driverless miles than any competitor. Its partnership with Uber for ride-hailing distribution gives it a demand channel without building a consumer app from scratch. Zoox remains in pre-commercial testing but benefits from Amazon's logistics infrastructure and data resources.
In China, Baidu's Apollo Go and Pony.ai have achieved commercial robotaxi operations in multiple cities, operating under a regulatory framework that has, in some respects, moved faster than U.S. state-level approvals. Pony.ai's recent public listing provided a public market valuation benchmark for the sector.
In Europe, the regulatory environment remains more fragmented, with national-level type approval processes slowing deployment timelines relative to Asia and parts of the U.S.
| Company | Region | Current Status | AI Stack Differentiator |
|---|---|---|---|
| Waymo | USA | Commercial, multi-city | Proprietary Waymo Driver, custom LiDAR |
| Zoox | USA | Pre-commercial | Bidirectional vehicle, end-to-end AI |
| Baidu Apollo Go | China | Commercial, multi-city | Open Apollo platform, government data access |
| Pony.ai | China/USA | Commercial (China) | Modular stack, recently public |
| Cruise (GM) | USA | Suspended, rebuilding | GM manufacturing scale |
The competitive dynamic is less about who has the best algorithm in isolation and more about who can accumulate the most diverse real-world driving data fastest — because that data is what trains the next model generation.
What This Means for Robotics
The robotaxi industry is functioning as an accelerated R&D program for physical AI — and the spillover effects are already visible in adjacent robotics markets.
For hardware buyers and fleet operators: The sensor and compute components being refined under the pressure of robotaxi economics are becoming available to industrial robotics integrators at falling price points. Solid-state LiDAR units that cost over $10,000 three years ago are now available under $500 from manufacturers like Livox and Ouster, directly because of volume driven by autonomous vehicle programs.
For robotics engineers: The transformer-based perception models and closed-loop simulation frameworks developed by Waymo and peers are being adapted for warehouse AMRs, surgical robots, and humanoid platforms. If your team is building embodied AI systems, the robotaxi industry's published research and open-source tooling (Baidu's Apollo platform remains partially open) represents a significant shortcut.
For investors and procurement teams: Autonomous fleet expansion requires support infrastructure — maintenance facilities, remote operations centres, charging networks, mapping services. Each of these creates procurement opportunities for used industrial robots in manufacturing and logistics applications that serve the AV supply chain.
The broader implication: robotaxis are not a consumer tech story. They are a physical AI deployment story at scale — and the lessons accumulating in San Francisco, Phoenix, and Shenzhen will shape how robots navigate hospitals, warehouses, and construction sites within the next product cycle. Those interested in how autonomous navigation is reshaping the hardware market should also browse humanoid robots on Robot Overflow to see how similar AI stacks are being applied to legged and wheeled platforms.