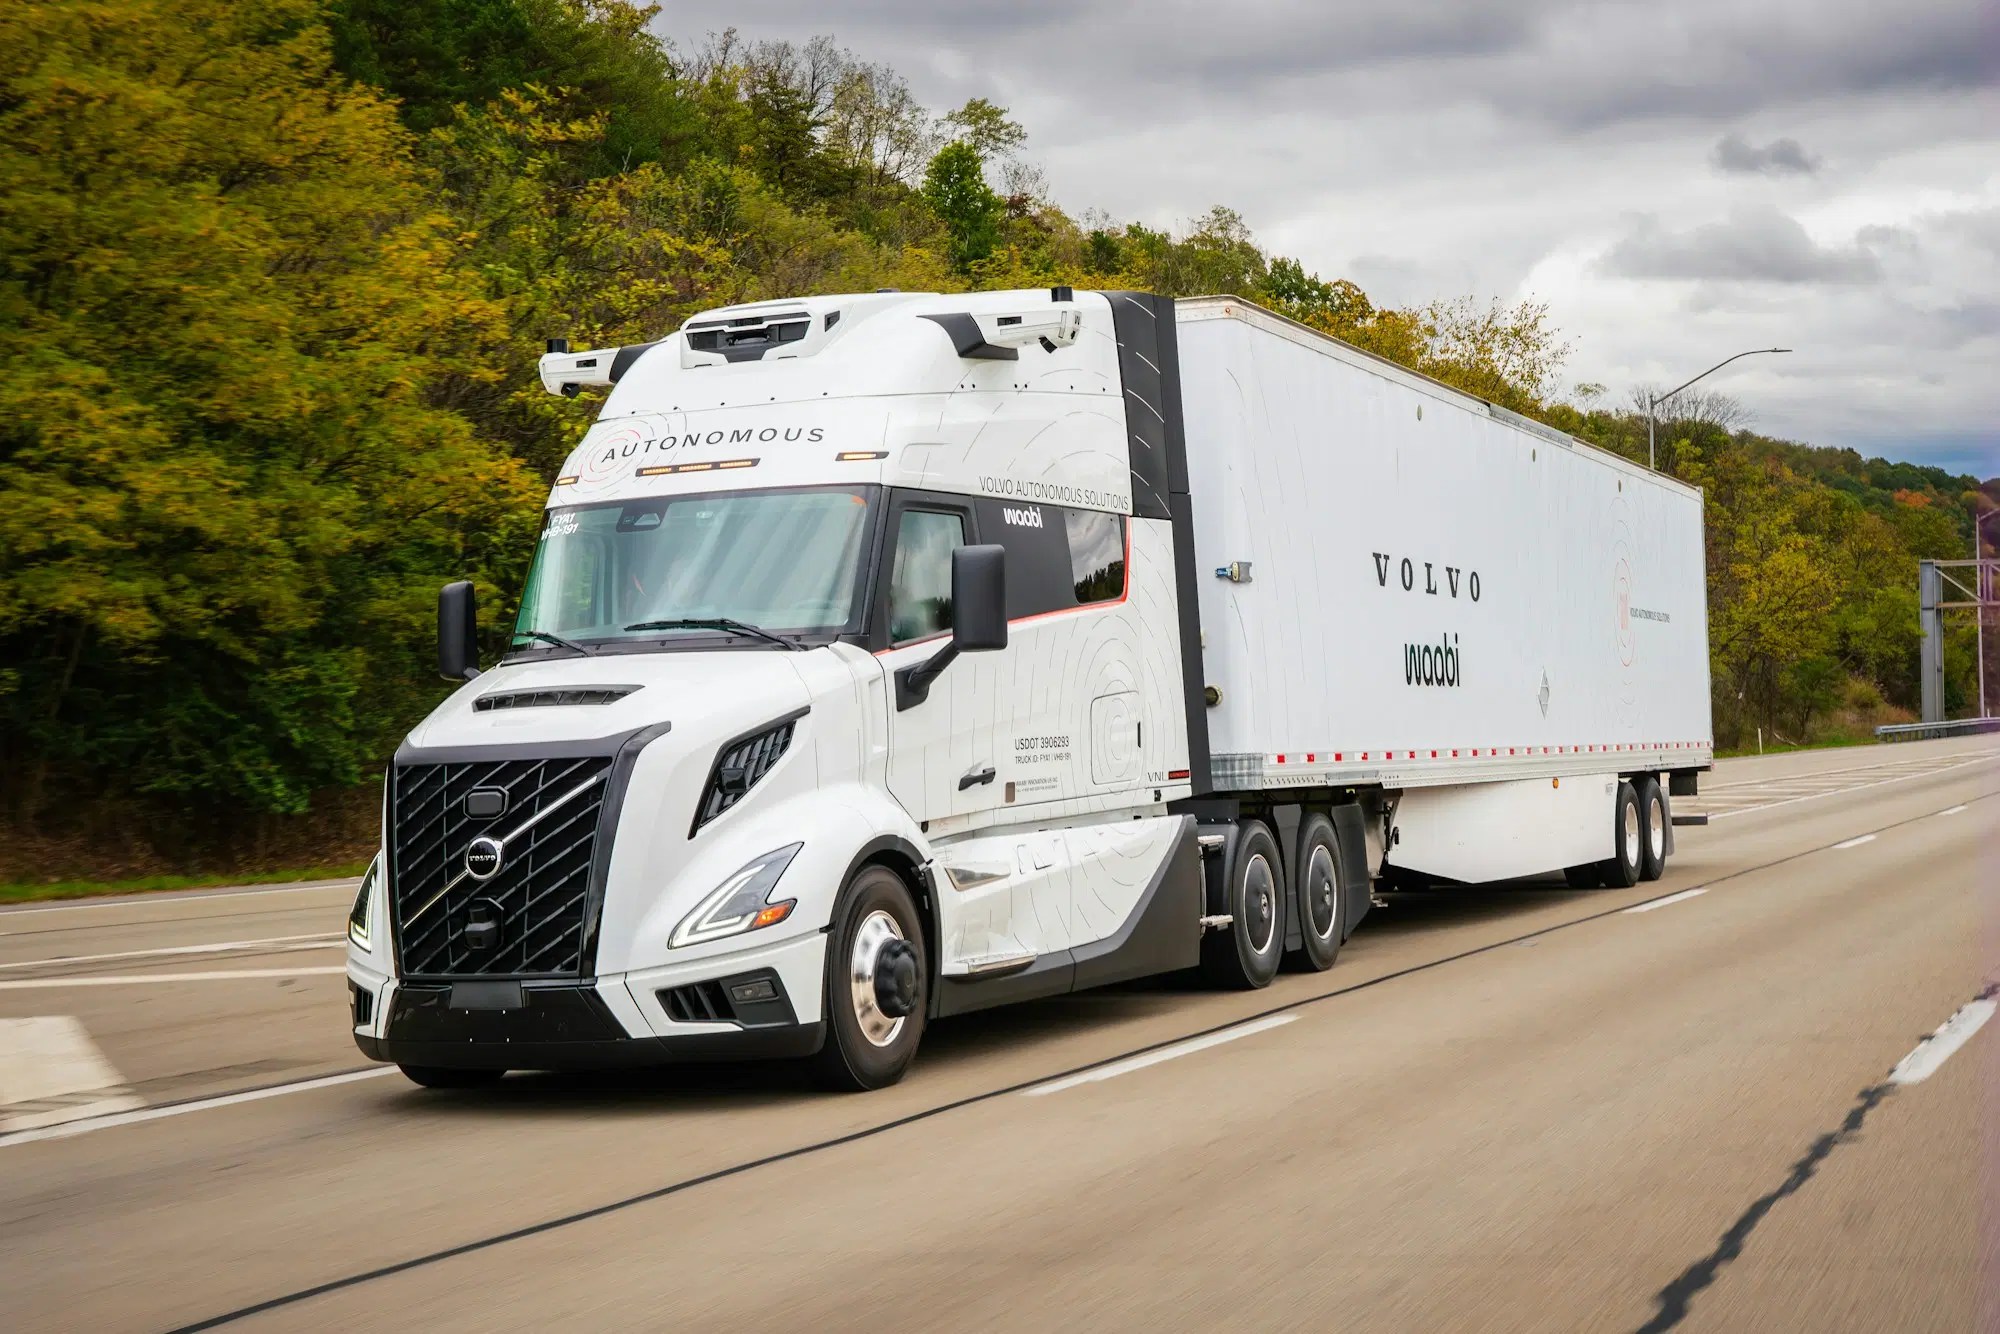

Autonomous trucking has crossed from perpetual "almost ready" into early commercial deployment — and Volvo Autonomous Solutions is among the first to prove it. As a global driver shortage squeezes logistics margins, the question is no longer whether driverless trucks will arrive, but who benefits and who gets left behind when they do.
Table of Contents
- What Is Volvo Autonomous Solutions Actually Deploying?
- How Severe Is the Trucking Driver Shortage?
- Driver Displacement vs. Driver Shortage: Who Really Wins?
- What Does Autonomous Truck Hardware Actually Cost?
- What This Means for Logistics Automation Buyers
- Frequently Asked Questions
What Is Volvo Autonomous Solutions Actually Deploying?
Volvo Autonomous Solutions is moving beyond closed-loop pilots into early commercial operations, targeting defined routes — hub-to-hub freight corridors and controlled industrial sites — where operational design domains (ODDs, the specific conditions a system is certified to handle) can be tightly managed. Rather than chasing full public-road autonomy immediately, the approach focuses on repeatable, high-frequency routes where the economics justify the hardware overhead today.
According to Robotics and Automation News, Volvo Autonomous Solutions frames the current deployment phase as the beginning of commercial reality — not a research programme. The distinction matters enormously for buyers evaluating capital commitments.
Their platform targets two primary environments:
- Hub-to-hub highway freight: Fixed origin-destination pairs on predictable road geometries, allowing sensor fusion stacks (combining LiDAR, radar, and camera inputs) to be trained and validated on a narrow but deeply understood environment
- Controlled industrial and port logistics: Geofenced areas where mixed traffic is minimal and regulatory friction is lowest
This staged strategy mirrors what Waymo Via and Aurora have pursued in the US — shrink the ODD to make autonomy commercially viable now, then expand. The critical difference is Volvo's integration advantage: the autonomous stack and the truck platform share a development lineage, which reduces the sensor-to-actuation latency that plagues third-party retrofit approaches.
How Severe Is the Trucking Driver Shortage?
The driver shortage is not a forecasting scenario — it is an active operational crisis reshaping logistics economics. The American Trucking Associations estimates the US industry was short approximately 60,000 drivers in 2023, a figure projected to exceed 80,000 by 2030 without structural intervention. Europe faces a parallel crisis: IRU (International Road Transport Union) data puts the European shortfall at over 400,000 drivers, with an ageing workforce accelerating the gap.
The economic consequences are direct and measurable. Driver wages now represent 30-40% of total trucking operating costs in most markets. Carriers running at partial capacity due to driver unavailability are leaving revenue on the table daily. Recruitment and retention costs have surged, with sign-on bonuses at major US carriers reaching $10,000-$15,000 per driver in competitive markets.
This is the structural tailwind that makes autonomous trucking commercially compelling independent of pure technology enthusiasm. The industry isn't adopting driverless trucks to cut existing jobs — it is filling roles that cannot be filled by humans at current wage levels and working conditions.
| Metric | US Market | European Market |
|---|---|---|
| Current driver shortfall | ~60,000 (2023) | ~400,000+ |
| Projected shortfall by 2030 | ~80,000 | ~700,000+ |
| Driver wages as % of operating cost | 30-40% | 25-35% |
| Average driver sign-on bonus (US, 2024) | $10,000-$15,000 | N/A (market varies) |
Driver Displacement vs. Driver Shortage: Who Really Wins?
This is where the narrative fractures — and where honest analysis requires holding two truths simultaneously. The driver shortage is real. So is the displacement risk. The question is which force dominates, and the answer depends heavily on deployment timeline and geography.
The shortage-first argument holds that autonomous trucks will absorb unfilled capacity before touching existing driver employment. If the industry cannot recruit 60,000-80,000 additional drivers in the US alone, autonomous systems enter a vacuum rather than a competitive displacement. This framing positions automation as additive — expanding the network's throughput ceiling without directly eliminating current roles.
The displacement-risk argument counters that automation doesn't respect the neat boundary between "vacancies" and "current workers." Route optimisation, hub consolidation, and autonomous hub-to-hub operations structurally reduce the total driver-hours needed per tonne-kilometre shipped. Even if no driver is directly fired, fewer total driving positions exist in an autonomously-optimised network. The economic incentive to replace a $75,000/year driver with a system that runs 22 hours a day without breaks is too strong to assume purely additive deployment.
The more likely reality is a two-speed transition. In geographies with acute shortages — rural US freight corridors, cross-border European logistics — autonomous trucks function as gap-fillers. In dense urban markets with established driver pools, the competitive displacement pressure is more direct, playing out over 5-10 years rather than 2-3.
What Volvo Autonomous Solutions' positioning signals is a deliberate choice to start where the shortage argument is strongest: defined industrial corridors where human drivers are already hard to recruit and retain. That is good strategy and good politics simultaneously.
What Does Autonomous Truck Hardware Actually Cost?
Autonomous truck deployments carry a hardware premium that makes total cost of ownership (TCO) analysis essential before any procurement decision. A conventional Class 8 semi-truck (the standard heavy freight category) sells new for $150,000-$200,000. Autonomous-capable platforms carry a significant premium.
Third-party autonomous kits — sensor arrays, compute platforms, and drive-by-wire interfaces — historically added $50,000-$150,000 per vehicle in early deployments, though costs are compressing rapidly as LiDAR unit prices fall (a high-performance solid-state LiDAR that cost $75,000 in 2019 now sells for under $1,000 at volume). OEM-integrated platforms like Volvo's eliminate retrofit complexity but are priced as complete systems.
Indicative autonomous trucking hardware cost ranges (2024-2025):
| Component | Entry Cost | Current Market Range |
|---|---|---|
| Base Class 8 truck (new) | $150,000 | $150,000-$200,000 |
| Autonomous sensor suite (LiDAR + radar + cameras) | $20,000 | $20,000-$80,000 |
| Compute platform (edge AI inference) | $8,000 | $8,000-$25,000 |
| Drive-by-wire interface kit | $5,000 | $5,000-$15,000 |
| Software licensing (annual, per vehicle) | $15,000 | $15,000-$40,000 |
| Total (retrofit path) | ~$198,000 | $198,000-$360,000 |
Used autonomous-capable truck components and legacy automated guided vehicle (AGV) hardware for port and industrial logistics applications are increasingly available through secondary markets — if you're evaluating entry points into industrial automation, used industrial robots on Robot Overflow can provide cost benchmarking context for adjacent automation hardware as prices continue to fall.
What This Means for Logistics Automation Buyers
For fleet operators, logistics directors, and supply chain technology buyers, Volvo Autonomous Solutions' commercial pivot signals that the evaluation window has shifted from "watch and wait" to "pilot or fall behind." The strategic implications are concrete.
Near-term (1-3 years): Hub-to-hub autonomous operations on fixed corridors are commercially available today from multiple vendors. The ROI case is strongest for operators running 3+ shifts per day on predictable routes — the elimination of driver hours, mandatory rest periods, and scheduling friction compounds quickly at this utilisation level.
Medium-term (3-7 years): ODD expansion will push autonomous capability toward mixed public-road operations, increasing deployment flexibility but also increasing regulatory complexity. Buyers who build operational experience with constrained autonomy now will have the institutional knowledge to scale when broader ODDs become available.
Technology stack considerations: Buyers evaluating autonomous trucking platforms should assess: - OEM-integrated vs. retrofit: OEM paths (Volvo, Daimler Torc, Paccar) offer tighter integration; retrofit paths offer platform flexibility - Connectivity dependency: Most commercial systems require 4G/5G connectivity for remote monitoring and intervention — infrastructure gaps on rural corridors remain a real constraint - Regulatory jurisdiction: US states vary significantly in driverless trucking regulations; EU is moving toward harmonised frameworks but timelines are uncertain
For buyers evaluating broader industrial automation strategy alongside trucking, used industrial robots on Robot Overflow offers visibility into the secondary market for automation hardware as first-generation deployments begin generating resale inventory.