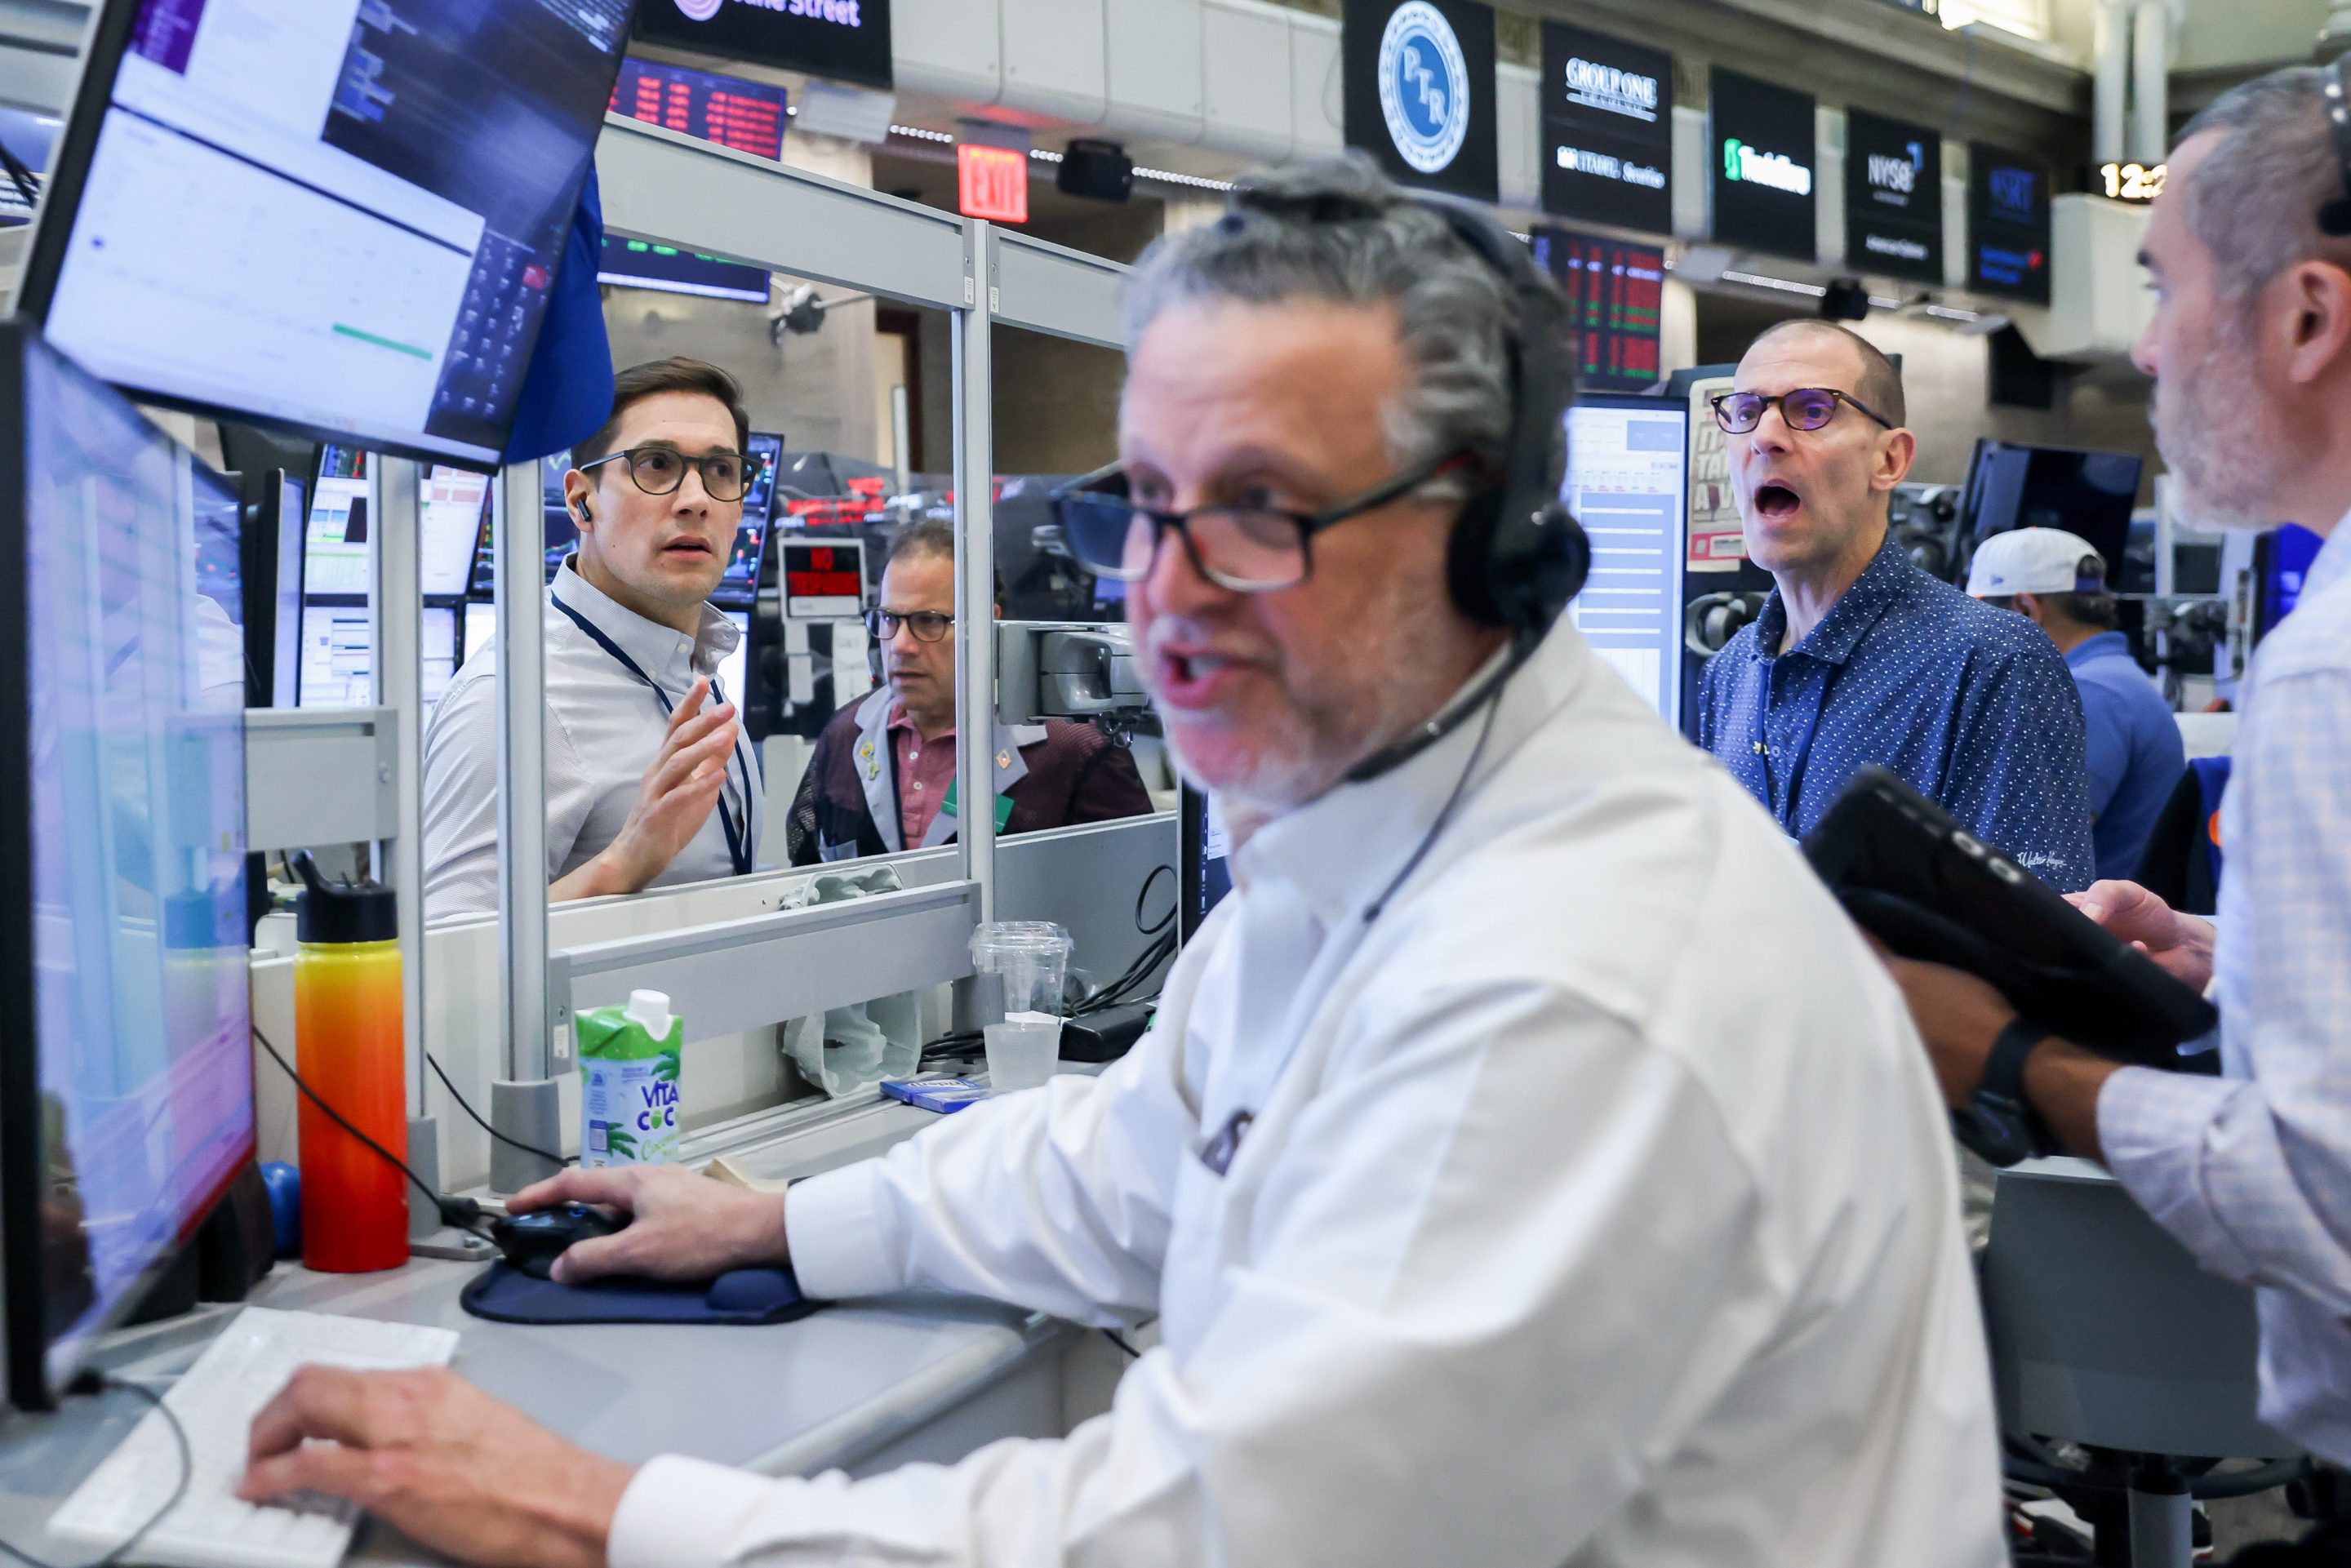
A stronger-than-expected May jobs report sent the Nasdaq down 4% on Friday, its worst day in over a year, as rising bond yields crushed high-growth tech stocks. The selloff signals that the market is repricing AI companies for a future of higher interest rates, putting pressure on the massive capital expenditure plans of hyperscalers.
- What Happened
- Why Strong Jobs Data Is Bad for Tech
- AI Stocks Hit Hardest
- What This Means for the Industry
- Frequently Asked Questions
- Conclusion
What Happened
The U.S. economy added nearly double the expected jobs in May, triggering a sharp selloff in technology stocks. The Nasdaq Composite fell 4% on Friday, its steepest single-day drop in over a year, while the S&P 500 slipped 1.2%. President Donald Trump questioned the market reaction on Truth Social, arguing that strong growth should boost stocks, not sink them.
But for markets, good news on the economy has become bad news. The combination of strong demand — overall spending grew 5.9% last quarter — and constrained supply from tariffs, the Iran war shutting oil shipments through the Strait of Hormuz, and a shrinking labor force due to immigration crackdowns has kept inflation above the Fed's 2% target for more than five years. The result: the Federal Reserve has no room to cut rates, and futures markets now price a better-than-60% chance of a rate hike by year-end.
Why Strong Jobs Data Is Bad for Tech
When supply is abundant, a strong jobs report signals more output and profits. But when supply is constrained, it signals more spending power pressing against the same inflation ceiling. That means the Fed stays hawkish, and longer-term interest rates rise. The 10-year Treasury yield jumped to 4.54% on Friday, while the 30-year crossed 5%.
Barclays' head of U.S. equity strategy, Venu Krishna, explained the dynamic to Fortune. Higher yields act as a "discount factor" on future profits. A stock's price is the present value of all future earnings — and when the risk-free rate rises, those distant profits are worth less today.
That hits technology companies hardest. AI stocks, many valued on revenue expected three to five years from now, sit at the far end of that duration spectrum. "Your discount factor is going up, and it shows up via pressure on valuation multiples," Krishna said.
AI Stocks Hit Hardest
The pain was concentrated in high-growth names. Memory chip makers Marvell and Micron fell 9% apiece. Meanwhile, the Dow Jones Industrial Average slipped just 0.3% as investors rotated into staples like Coca-Cola and Colgate-Palmolive — companies whose profits arrive now, not years in the future.
Barclays' research identifies 5% on the 10-year Treasury as a key level. At 4.54%, "we are in the warning zone, but just in the warning zone," Krishna said. "Five percent is more of a clear level. But as we start approaching it, the market starts pricing that risk."
The selloff also reflects market froth. Barclays tracks speculative activity across 700 stocks using an options market index. Historically, about 7% of stocks show signs of speculative chasing. That share recently climbed to roughly 10%. The last time it ran meaningfully higher, reaching 14% earlier this year, the March selloff followed.
Despite the selloff, Krishna does not see it as the end of the AI trade. Hyperscalers trade near 26 times forward earnings, cheaper than they were in January despite stronger profits. He called a further dip "a huge buying opportunity." The pressure instead concentrates on companies whose valuations rest mostly on the future — not because their business models are falling apart, but because the discount rate is rising.
What This Means for the Industry
The recent repricing comes at a critical moment for the IPO pipeline. SpaceX is set to debut at a $1.77 trillion valuation, the largest IPO in history, priced on years of growth yet to come. Anthropic has filed its confidential prospectus, and OpenAI is in the rearview mirror. Analysts worried there might be too much supply of stocks and not enough buyers. Friday's selloff eases those concerns slightly by bringing valuations down.
For the broader tech industry, higher rates mean more expensive capital. The hyperscalers are on pace to spend close to $1 trillion a year on data centers and chips. Even Alphabet raised $85 billion from the stock market to fund its AI buildout. Rising borrowing costs could force companies to prioritize efficiency or delay non-essential projects.
However, the selloff may also impose necessary discipline. As Krishna noted, markets are more euphoric than ever, with speculative indicators at elevated levels. A reset could shake out excess and set the stage for a healthier rally in companies with real earnings power.
Conclusion
Friday's selloff is not a crash but a recalibration. The AI trade remains intact, but the era of cheap money is winding down. Investors are demanding that companies prove their worth in the present, not just promise it for the future. For the tech industry, the message is clear: growth alone is no longer enough — profitability and discipline matter more than ever.