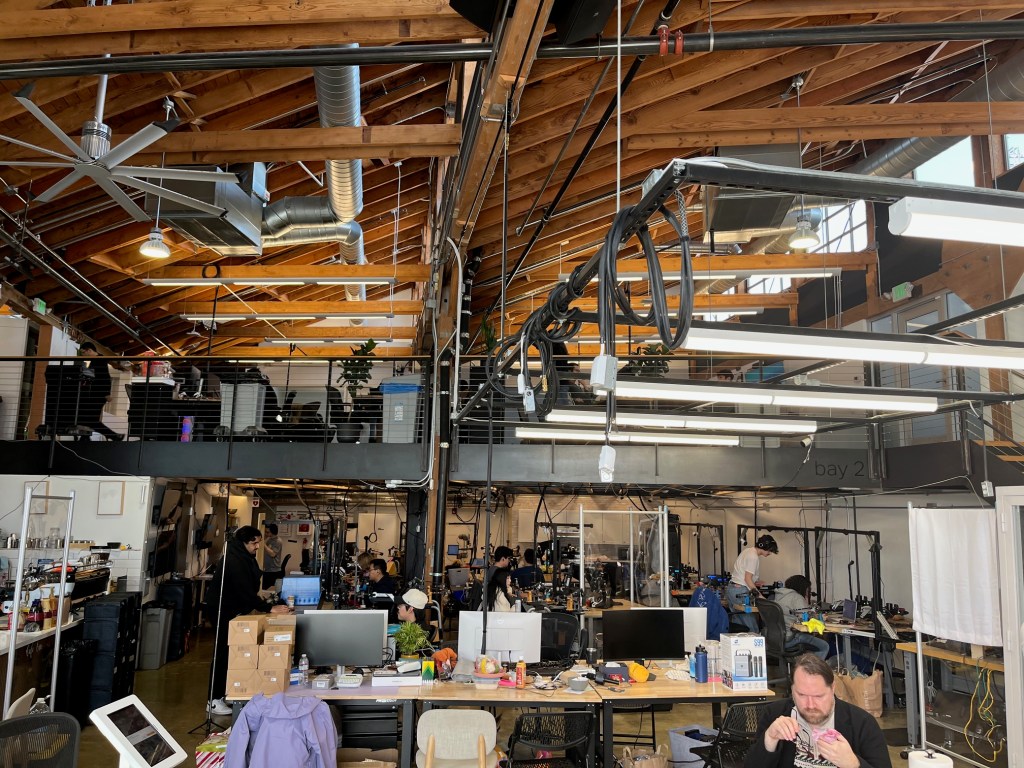
Physical Intelligence (π) is reportedly in talks to raise $1 billion at an $11 billion valuation, effectively doubling its worth in under four months — a trajectory that illustrates a stark bifurcation in the robotics market between foundation model platforms and the hardware companies struggling to ship reliable products.
Table of Contents
- What is Physical Intelligence and why is it raising again?
- Why is Physical Intelligence's valuation doubling so fast?
- What does this mean for the broader robotics funding landscape?
- Physical AI foundation models vs. robot hardware: the market split
- What This Means for Robotics
- Frequently Asked Questions
What is Physical Intelligence and why is it raising again?
Physical Intelligence is an AI startup building general-purpose foundation models for robot control — software that can train robots to manipulate physical objects across diverse environments without task-specific programming. According to TechCrunch, the company is in active discussions to close a $1 billion round at a valuation of approximately $11 billion.
The company raised at a $5.6 billion valuation just four months prior. Raising again this quickly — and at nearly double the price — is unusual even by Silicon Valley standards. It signals that investor conviction around Physical AI foundation models isn't just holding; it's compounding faster than almost any other category in tech right now.
π's core product is a policy model: software trained on vast datasets of robotic manipulation to generalise across tasks. Think of it less like a robotics company and more like an OpenAI for robot hands.
Why is Physical Intelligence's valuation doubling so fast?
The simple answer: Physical AI foundation models are being repriced from "interesting research" to "critical infrastructure." Investors funding π aren't betting on a single robot — they're betting on the layer that makes every robot smarter.
Three forces are compressing the valuation timeline:
1. Demonstrated generalisation π's published research showed its π0 model handling laundry folding, table bussing, and box assembly with a single pre-trained policy. Achieving cross-task generalisation — long the holy grail of robot learning — in a deployable model is a credible technical milestone, not a roadmap promise.
2. Platform economics A foundation model trained once can be fine-tuned and sold to dozens of hardware partners. The marginal cost of adding a new robot OEM as a customer is low; the revenue from licensing or API access scales with adoption. Investors recognise this as a fundamentally different business model than selling individual robot units.
3. Competitive urgency Google DeepMind's RT-2, Figure's OpenAI partnership, and Agility Robotics' in-house learning stack are all racing toward the same general-purpose manipulation capability. Capital is the moat-builder when the technical race is this tight. Sitting out a funding round means ceding ground to rivals who will use cash to acquire training data, compute, and talent.
What does this mean for the broader robotics funding landscape?
The π fundraise is the most visible data point in a pattern of extreme capital concentration. A small number of Physical AI platform companies are capturing a disproportionate share of available investment, while many hardware-first robotics companies face flat or down rounds.
| Company Type | Recent Funding Trajectory | Valuation Trend |
|---|---|---|
| Physical AI foundation models (π, etc.) | Multiple large rounds in rapid succession | Sharply upward |
| Humanoid hardware startups | Mixed — selective large rounds for leaders | Bifurcated: top 2-3 surge, rest flatten |
| Cobot / industrial robot OEMs | Slower, more strategic rounds | Stable to modest growth |
| Single-use robotics (delivery, cleaning) | Compressed; some down rounds | Declining for undifferentiated players |
The implication is that the market is pricing the AI layer as primary value and the hardware as a commodity. This doesn't mean hardware is irrelevant — robots still need to work reliably in the physical world. But it does mean that companies which own the intelligence layer, not just the mechanical platform, are capturing the majority of investor excitement.
There's a parallel to what happened in cloud computing a decade ago: the underlying servers became increasingly commoditised while the software platforms running on top of them commanded premium multiples. The robotics industry may be entering the same transition.
Physical AI Foundation Models vs. Robot Hardware: The Market Split
The emerging bifurcation deserves a closer look, because it will shape which companies survive the next shakeout.
The case for foundation model dominance
A universal manipulation policy, if it genuinely achieves broad generalisation, removes the single most expensive line item in robotics deployment: custom integration. Today, deploying a robot arm for a new industrial task typically requires weeks or months of task-specific programming, simulation setup, and on-site calibration. A foundation model that can be fine-tuned in hours collapses that cost dramatically.
This is why enterprise buyers — logistics operators, contract manufacturers, food processors — are watching π and its competitors closely. The economics of automation improve radically if the software integration cost approaches zero.
The risk: generalisation is harder than it looks
Every demonstration of cross-task generalisation has been conducted in controlled or semi-controlled environments. The gap between "works in a well-lit lab with consistent object placement" and "works on a factory floor with variable lighting, worn tooling, and unexpected object states" remains substantial.
π's $11 billion valuation is pricing in successful generalisation at commercial scale. If that proves harder to achieve than the research suggests, the correction will be severe. Foundation model valuations are built on future distribution, and distribution requires reliability that hasn't yet been demonstrated in adversarial real-world conditions.
Hardware still matters — but differently
The companies likely to benefit most from foundation model progress are those building robots as platforms: open, sensor-rich, designed for software iteration. Humanoids with standardised interfaces, cobots with modern APIs, and mobile manipulators with clean ROS 2 stacks will be easier to plug into a π-style policy layer than proprietary, closed systems.
For buyers evaluating robot hardware today, the question is less "what can this robot do right now?" and more "how easily can this platform absorb better AI as the models mature?"
What This Means for Robotics
The π fundraise is a signal worth acting on for everyone in the robotics ecosystem — not just investors.
For robot buyers and integrators: The economics of AI-assisted deployment are changing faster than procurement cycles. Platforms that can connect to general-purpose policy models will deliver compounding capability improvements over their installed life. Factor software upgradeability into hardware decisions now. If you're evaluating industrial robots or cobots, ask vendors explicitly about their AI integration roadmap and API openness.
For hardware startups: Competing on manipulation intelligence alone is increasingly difficult against well-capitalised foundation model labs. The defensible position is either (a) owning a specific hardware niche that foundation models will need to run on, or (b) owning proprietary training data from real-world deployments — something pure software labs cannot easily replicate.
For enterprise adopters: The near-term practical impact of foundation models in production environments is likely 18-36 months out for most applications. But the time to evaluate platforms, establish vendor relationships, and begin small-scale pilots is now — before the technology matures into a procurement bottleneck.